Act of Congress Redmont Commerce and Finance Act

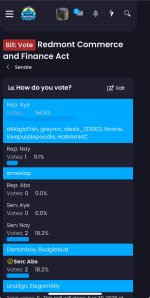
How do you vote?

  • Rep: Aye

    Votes: 0 0.0%
  • Rep: Nay

    Votes: 0 0.0%
  • Rep: Abs

    Votes: 0 0.0%
  • Sen: Nay

    Votes: 0 0.0%

  • Total voters
    3
  • Poll closed .

greymc

Moderator
Moderator
Vice President
Congressional Staff
Supporter
Oakridge Resident
State Department
Homeland Security Department
Interior Department
Education Department
Justice Department
Health Department
_GreyMC
_GreyMC
Vice President
Joined
May 23, 2026
Messages
1,008

CONGRESS OF THE
COMMONWEALTH OF REDMONT

​


A BILL TO
Restate the Law of Legal Entities
​


The people of the Commonwealth of Redmont, through their elected Representatives in the Congress and the force of law ordained to that Congress by the people through the constitution, do hereby enact the following provisions into law:
​
PART I — PRELIMINARIES

1. Short Title and Enactment

(1) This Act may be cited as the 'Redmont Corporate Entities Act' or the 'RCEA'.
(2) This Act shall be enacted immediately upon its signage.
(3) This Act has been authored by President Theory Fontaine, Commerce Secretary Planke Fontaine, and FRB Governer Coshjlose.
(4) This Act has been co-sponsored by Senator ElegantAlly.
(5) This Act repeals and replaces the following act:
(a) Legal Entity Act
(6) This Act amends the following acts:
(a) Bankruptcy Act

2. Reasons and Intent
(1) The law of legal entities is spread across the Legal Entity Act, the Commercial Standards Act, the Financial Institutions Enforcement Act and the Banking Income Tax Act. Provisions duplicate, contradict and cross-amend each other, and no reader can find the rule that applies to them in one place.
(2) The paperwork burden falls hardest on the smallest businesses. A player who wants to run a shop with a friend must currently produce a certificate, bylaws, a register, a summary and a stream of docket filings, or else operate with no liability protection at all.
(3) Redmont recognises only two private forms, the corporation and the LLC. Ordinary commercial arrangements such as partnerships, member owned cooperatives and purpose bound foundations have no home in law.
(4) The law protects shareholders and creditors far less than the continental practice Redmont's economy has grown to resemble. There is no rule against paying out capital a company does not have, no pre-emption right when a majority dilutes a minority, no exit for a minority once control has changed hands, and no duty on directors to stop trading once the entity is insolvent.
(5) Modern corporate practice, including written consent in place of a meeting, electronic notice, supervisory boards, group structures and conversion between entity forms, is not provided for.
(6) The Department of Commerce can punish, but it cannot repair. It has no inspectors, no power to strike a dead entity off the register or restore it, and no power to put a director into an abandoned company so that its creditors can be paid.
(7) This Act therefore restates the whole law of legal entities in one place, adds a Standard Form incorporation that takes a single post, adds partnerships, cooperatives and foundations, imports the continental protections named above, gives the Department the powers of a real registrar, and cuts the mandatory filing list to what a creditor or a court actually needs.

3. Definitions
(1) For the purposes of this Act:
(a) Agent. A person acting on behalf of a legal entity, including a director, manager, officer, employee or contractor so acting. It does not include a legal representative acting in that capacity, nor an interest holder acting only in that capacity.
(b) Authorised Shares. All shares a corporation is permitted to issue under its formation instrument.
(c) Characteristic. The voting powers, whether full, limited or absent, and the designations, preferences, rights, qualifications, obligations, conditions, limitations and restrictions attaching to a share, membership or other interest.
(d) Consolidation. A procedure by which two or more entities combine into a new entity created by that procedure.
(e) Constituent Entity. An existing entity participating in a merger, consolidation or division.
(f) Depositary Receipt. An instrument issued by a Depositary Foundation that confers the economic benefit of an underlying share or membership interest without conferring the voting power attaching to it.
(g) Distributable Reserves. Accumulated realised profits not previously distributed or capitalised, less accumulated realised losses not previously written off, and less any amount the formation instrument requires to be retained.
(h) Entity. A legal entity.
(i) Entity Profile. The first post in an entity's record in the Company Register, as described in Part III.
(j) Filed. Posted in the entity's record in the Company Register.
(k) Formation Instrument. The instrument that forms a legal entity and governs it, being the Certificate of Incorporation of a corporation, the Certificate of Formation of an LLC, the Partnership Agreement of a partnership, the Certificate of Cooperation of a cooperative, the Certificate of Foundation of a foundation, or the enactment forming a governmental entity.
(l) Foundation. An Incorporated Entity that has no members and no interest holders, whose assets are bound to the purpose stated in its Certificate of Foundation.
(m) Incorporated Entity. A corporation, a limited liability company, a limited partnership, a limited liability partnership, a cooperative, a foundation or a non-profit formed under this Act.
(n) Individual. A natural person.
(o) Insider. In relation to an entity, a director, manager, general partner, officer, member of a Supervisory Board, a person holding more than 10% of its voting power, a person who exercises dominant influence over it within the meaning of section 31(1)(c), a founder or beneficiary of a foundation, and any entity controlled by any of them. This definition applies for the purposes of the Bankruptcy Act where that Act refers to the term as used in this Act.
(p) Interest Holder. A shareholder of a corporation, a member of an LLC, a cooperative or a non-profit, or a partner of a partnership. A foundation has no interest holders.
(q) Manager. A person designated to manage an LLC.
(r) Member. The holder of a membership interest in an LLC, cooperative or non-profit.
(s) Outstanding Shares. All shares of a corporation other than those held by the corporation itself.
(t) Person. An individual, an entity, or a House registered under the Redmont Family Law Act.
(u) Public Company. A company whose securities are listed on a registered Stock Exchange, as defined in the Commercial Standards Act.
(v) Registered Name. The name of a legal entity as stated in its formation instrument.
(w) Resolution. A decision taken by vote or by written consent under Part V.
(x) Shareholder. The holder of a share in a corporation.
(y) Standard Form. The default formation instrument published by the Department of Commerce under Part IV.
(z) Supervisory Board. A body established under section 28 to supervise the management of an entity.
(aa) Voting Power. The total votes attaching to all shares, memberships or partnership interests entitled to vote on the matter in question.
(bb) Winding Up. The process of settling an entity's affairs before dissolution.

4. Interpretation
(1) Where a provision of this Act applies "unless otherwise provided", it may be displaced by the formation instrument, and where the formation instrument delegates the subject matter to bylaws or an internal agreement, by those bylaws or that agreement.
(2) The economic substance of an arrangement prevails over its label.
(3) A reference to a document being signed, given, sent or posted is satisfied by any durable and attributable electronic means, including a forum post, an in game book or a message in a channel the recipient can access.
(4) Where this Act requires a period of days, the period runs from the moment the triggering act occurs.
(5) Where a provision admits more than one reading, the reading that keeps the entity operating, protects creditors and avoids forfeiture of rights on a technicality is preferred.
(6) A failure to observe an internal formality is not, of itself, a ground for invalidating an act of the entity or for imposing liability on any person.
(7) A provision of Parts XI, XII or XIX may not be displaced by the formation instrument except where that Part expressly allows it.

PART II — PROVISIONS COMMON TO ALL LEGAL ENTITIES

5. Legal Personality

(1) A legal entity is a legal person with rights and liabilities strictly distinct from those of its interest holders and agents.
(2) A legal entity has perpetual existence unless its formation instrument provides otherwise.
(3) The forms of legal entity recognised in Redmont are:
(a) the sole proprietorship;
(b) the general partnership;
(c) the limited partnership;
(d) the limited liability partnership;
(e) the limited liability company;
(f) the corporation;
(g) the cooperative;
(h) the foundation;
(i) the non-profit; and
(j) the governmental entity.

6. Powers
(1) A legal entity has the capacity, rights and powers of an individual, and may do anything lawful in furtherance of any purpose, whether or not that purpose is stated in its formation instrument and whether or not the act benefits the entity.
(2) Without limiting subsection (1), a legal entity may:
(a) sue and be sued in its own name, and take part in any judicial or administrative proceeding;
(b) acquire, hold, improve, use, lease, sell, mortgage, pledge and otherwise deal in property of any kind, wherever situated;
(c) hold, vote and deal in shares, memberships, bonds, debts and other interests issued by any person;
(d) make contracts, give guarantees, incur liabilities, borrow and lend at any rate of interest, and secure its obligations over any of its property;
(e) carry on business and hold offices anywhere within or outside Redmont;
(f) appoint and remove agents, define their duties, set their compensation and indemnify them;
(g) be an incorporator, interest holder or agent of any other entity;
(h) make donations for public, charitable, educational, civic, sporting or similar purposes;
(i) renounce any interest or expectancy in a business opportunity;
(j) adopt, amend and repeal its formation instrument and any bylaws;
(k) wind up and dissolve itself; and
(l) in the case of a corporation, deal in its own shares, subject to Part XI.
(3) The powers in this section may be limited by the formation instrument, and a limitation so imposed binds the entity and its agents internally but does not affect a third party except as provided in section 10.
(4) A foundation may exercise the powers in this section only in furtherance of its stated purpose.

7. Names
(1) No person may register a legal entity, or an in game company, under a name that could cause serious confusion with an existing legal entity.
(2) The Department of Commerce (DOC) may refuse or require the change of a name that contravenes subsection (1), that falsely implies governmental status, or that falsely implies a licensed activity the entity is not licensed to carry on.
(3) A change of registered name does not abate any legal action brought by or against the entity under its former name.
(4) The DOC shall refuse to register a legal entity, or an in game company, under a name that contains or is confusingly similar to a family name registered under the Redmont Family Law Act, unless the family consents, and shall require the change of any such name on the application of the family where that Act so provides.

8. In Game Companies
(1) An Incorporated Entity must maintain a corresponding in game company in the business plugin, except where the DOC waives that requirement by rule for a class of entity.
(2) The Incorporated Entity sets the owner of the in game company and may request the DOC to change that owner at its pleasure.
(3) Ownership of an in game company does not, of itself, make a person an interest holder or agent of the associated Incorporated Entity. That presumption may be rebutted on the balance of probabilities.
(4) The DOC may change the owner of, or disband, an in game company used to carry on or disguise activity in contravention of the Commercial Standards Act or this Act.

9. Fiduciary Duty
(1) An agent of an Incorporated Entity must act:
(a) in good faith;
(b) on an informed basis;
(c) with the care a reasonable person in a similar position and circumstance would exercise; and
(d) in a manner the agent reasonably believes to be in the best interests of the entity and, by extension, of its interest holders or, in the case of a foundation, of its purpose.
(2) An agent who has a conflict of interest and has disclosed it, or whose conflict is known to the relevant parties, is presumed to have acted in the best interests of the entity.
(3) The court shall presume the fiduciary duty has been met, subject to rebuttal by clear and convincing evidence of a breach causing damage.
(4) A court shall not substitute its own judgement on a matter of business judgement, except where there has been a breach of fiduciary duty or criminal or unlawful conduct.
(5) A claim for breach of fiduciary duty may be brought by a contractual party owed the duty, an interest holder of the entity, a creditor of the entity while it is insolvent, or the DOC.
(6) An agent is fully protected in relying in good faith on the records of the entity and on information, opinions, reports or statements presented by an agent of the entity or by another person as to matters the agent reasonably believes are within that person's competence.

10. Agency and Authority
(1) A contractual party or third party may presume that a director, manager, officer or partner who purports to bind the entity has the power to do so.
(2) The entity is bound notwithstanding that the person lacked the power, and the entity may recover its damages from that person.
(3) The entity is not bound where the counterparty knew, or had been given notice, that the person lacked the power.

11. Liability
(1) An Incorporated Entity is solely liable for its own debts, obligations and liabilities.
(2) Unless liability has been voluntarily assumed by the person against whom it is asserted, no interest holder or agent of an Incorporated Entity is liable for the entity's debts, obligations or liabilities, whether in contract, tort or otherwise:
(a) solely by reason of being an interest holder or agent; or
(b) by the acts or omissions of another interest holder or agent.
(3) A failure to observe the usual formalities of governance is not a ground for imposing personal liability.
(4) Any person may voluntarily assume liability for any or all of an entity's debts and obligations.
(5) Acts and resolutions of interest holders in that capacity are attributable exclusively to the entity.
(6) Notwithstanding subsections (1) to (3), the Federal Court may impose personal liability for the debts, obligations or liabilities of an Incorporated Entity on an interest holder or agent who used the entity:
(a) to commit fraud;
(b) to evade the law or an existing obligation; or
(c) as a mere instrument or alter ego whose affairs were commingled with their own.
(7) The DOC may bring a claim under subsection (6).
(8) This section is subject to the personal liability imposed by Parts XI and XIX.

12. Access to Information
(1) Unless otherwise provided, each director, manager, general partner and member of a Supervisory Board has unrestricted access to information regarding the business, financial condition and affairs of the entity.
(2) Unless otherwise provided, each other interest holder has reasonable access to that information.
(3) A director, manager or officer may withhold information from interest holders, for such period as is reasonable, where they reasonably believe the information:
(a) is in the nature of a trade secret;
(b) would damage the entity or its business if disclosed, or that disclosure is not in the entity's best interests; or
(c) is required to be kept confidential by law or by agreement with a third party.
(4) An Incorporated Entity shall, on request of the DOC, disclose the beneficial owners of its shares or memberships, being the individuals who ultimately own or control them, including where they are held through a nominee, custodian, exchange or Depositary Foundation.

13. Legal Process
(1) A summons of an Incorporated Entity must summon, in order of priority:
(a) the individual designated in the Entity Profile to receive legal communications, where that individual has accepted the designation and has joined the server within the previous 30 days;
(b) failing that, the directors, managers or general partners of the entity;
(c) failing that, where ten or fewer persons hold voting power, all of them; or
(d) failing that, the largest holders of voting power in descending order until, if possible, more than 50% of total voting power is summoned.
(2) Any other legal process or communication is presumed delivered if delivered:
(a) to the individual designated in the Entity Profile;
(b) to a director, manager or general partner who has joined the server in the previous 30 days; or
(c) by a filing in the Company Register.
(3) The court clerk, or the presiding judicial officer, shall file the summons in the entity's record. The summons becomes active on that filing.

14. Criminal and Civil Treatment of Entities
(1) A sentence of imprisonment imposed on a legal entity is converted into an additional fine of 10 penalty units per minute.
(2) A governmental entity shall not be issued any criminal punishment other than a declaration of guilt.
(a) This does not affect the power of a court to issue injunctions and orders, or to enforce them.
(b) A governmental entity may be held civilly liable for torts arising from a violation of criminal law.

PART III — THE COMPANY REGISTER

15. The Register

(1) The Company Register holds a public record for each Incorporated Entity, in the form of a thread titled with the entity's registered name.
(2) The function of the record is to give creditors, counterparties, interest holders and the courts a single reliable place to find who controls the entity, what its constitution says, and what is being litigated against it.
(3) Information filed in the record is permanent and may not be edited, except that an immaterial mistake such as a typographical error may be corrected shortly after posting if the correction does not alter the meaning of the record.
(4) A document filed in the record must be stored in a medium that is itself permanent and immutable. Editable external links, including shared document links, may not be used.
(5) The Entity Profile may be edited, but only to restate information that is supported by a filing made under section 16.
(6) A document required to be filed under this Act must be:
(a) uploaded as a PDF attachment to such a post through the forum's own attachment system.
(7) A hyperlink to a document, or a document held on any external service, is not a filing, does not satisfy any requirement of this Act, and the entity is treated as not having filed the document.
(8) An attachment filed under subsection (6)(b) may not be replaced or removed. Replacing or removing it is a failure to file, and the entity shall file the document afresh. Where an attachment becomes unavailable, the entity shall file the document afresh within 7 days of notice from the Department or from any person with an interest.
(9) A post filing a document by attachment must state in text the nature of the document, the date it was adopted, and the provisions it creates, alters or removes.

16. Mandatory Filings
(1) The following must be filed in an entity's record:
(a) the formation instrument, and any amendment to it, an amendment being filed by setting out only the provisions created, altered or removed, showing the text of each before and after the amendment;
(b) the appointment, election, removal or resignation of a director, manager, general partner, officer or member of a Supervisory Board, stating the person's name and title;
(c) a summons of the entity, and the verdict in any case in which the entity was a party;
(d) a resolution approving a dissolution, a Certificate of Merger, Consolidation, Division or Conversion, and a Certificate of Dissolution;
(e) the issue, transfer or cancellation of shares or memberships, including a transfer under an order of a court made under the Redmont Family Law Act, which takes effect on filing, except where the interest remains in the custody of a registered exchange; and
(f) a notice required by Part XI or Part XIX.
(2) A filing under subsection (1)(e) may be made as a single consolidated filing covering all transfers in a calendar month.
(3) The entity is responsible for making the filings required by subsections (1)(a), (1)(b), (1)(d), (1)(e) and (1)(f). The court is responsible for those required by subsection (1)(c). A person who has resigned, or who has been removed, may make the filing of their own resignation or removal, and it takes effect on that filing.
(4) An entity may file anything else in its record, including resolutions, votes, notices and announcements, and a filing so made carries the same evidential weight as a mandatory filing.
(5) An act for which a filing is required takes effect from the moment the filing is posted, unless this Act or the filing provides for a later effective time.
(6) A filing obligation may be added only by an Act of Congress or by a rule made under section 76, and a rule may not impose a filing obligation on an entity exempted by section 76(3).
(7) An Incorporated Entity shall file a consolidated text of its formation instrument, incorporating every amendment to date, on the request of the Department and in any event on making its fifth amendment since the last consolidated text was filed.

17. The Entity Profile
(1) The first post in an entity's record is the Entity Profile, which the entity shall keep current without undue delay. Every change to a register held in the Entity Profile must be supported by a filing under section 16, and a register entry that no filing supports is not evidence of the matter it records.
(2) The Entity Profile shall state:
(a) the registered name and the name of the associated in game company;
(b) the entity's form under section 5(3);
(c) the current directors, managers or general partners, the members of any Supervisory Board, and the officers with their titles;
(d) the current consolidated text of the formation instrument, set out in full or attached under section 15(6)(b);
(e) the share register, member register or partner register, as applicable; and
(f) any ongoing court case or regulatory enforcement action.
(3) The Entity Profile may designate an individual to receive legal correspondence on the entity's behalf.
(4) A person dealing with the entity may rely on the Entity Profile, and the entity may not assert against that person any fact the Profile contradicts, unless the person had actual notice of the true position.
(5) An entity formed on the Standard Form satisfies subsection (2)(d) by stating that it is formed on the Standard Form and listing any elections it has made.
(6) The text held under subsection (2)(d) must reflect every amendment filed under section 16(1)(a). Where it does not, the filed amendments prevail, except in favour of a person relying on the Entity Profile under subsection (4).

PART IV — FORMATION

18. Formation

(1) An Incorporated Entity is formed by filing its formation instrument in a new record in the Company Register.
(2) A formation instrument must state:
(a) the registered name of the entity;
(b) its form under section 5(3);
(c) the name of each incorporator;
(d) the name of the associated in game company, if applicable; and
(e) the purpose of the entity, and except in the case of a foundation it is sufficient to state that its purpose is to engage in any lawful activity.
(3) A formation instrument may state anything else not contrary to law, and in particular may:
(a) provide for the management of the entity and the conduct of its affairs, including the establishment of a Supervisory Board;
(b) create, define, limit and regulate the powers of the entity, its agents, its interest holders and any class of them;
(c) require a larger vote than this Act requires;
(d) limit the entity's existence to a fixed term;
(e) impose personal liability on interest holders to a specified extent and on specified conditions;
(f) set the characteristics of any class of interest or of any agent;
(g) set conditions for the admission, removal or forfeiture of interests; and
(h) name the first directors, managers, partners or members.
(4) Where a formation instrument delegates a subject matter to bylaws or an internal agreement, a reference in this Act to the formation instrument includes that document. In case of conflict, the formation instrument prevails.
(5) Unless otherwise provided, the board or the managers may amend the bylaws by a majority.
(6) There is no requirement to adopt bylaws.

19. Standard Form Incorporation
(1) The DOC shall publish a Standard Form formation instrument for each form of Incorporated Entity.
(2) An entity is formed on the Standard Form by filing a single post stating:
(a) the matters required by section 18(2);
(b) that the entity adopts the Standard Form for its form of entity; and
(c) any election the Standard Form permits.
(3) A Standard Form entity has the governance, ownership and default rules set out in this Act, and requires no bylaws, no separate certificate document and no further formation filing.
(4) A Standard Form entity may at any time adopt a bespoke formation instrument by amendment under section 21, and a bespoke entity may adopt the Standard Form by the same route.
(5) The Standard Form is a rule of the DOC and is subject to section 76. A change to the Standard Form does not alter the constitution of an entity already formed on it unless that entity resolves to adopt the change.

20. Review and Deemed Approval
(1) The DOC may reject the formation of an Incorporated Entity for a clear and justifiable reason related to the formation filing, including a name that contravenes section 7.
(2) A rejection must be filed in the entity's record within 14 days of the formation filing, and must state the reason and the steps required to cure it.
(3) Where the DOC does not reject a formation within 14 days, the entity is formed and its formation is deemed approved.
(4) An entity whose formation is rejected may cure the defect and refile, and the period in subsection (3) runs afresh from the refiling.
(5) This section applies, with the necessary changes, to any approval, signature or verification this Act requires of the DOC, other than the signature of a Certificate of Dissolution, a Certificate of Merger, Consolidation or Division, or a Certificate of Conversion.
(6) A Certificate to which subsection (5) does not apply takes effect only on the actual signature of the Secretary of the DOC or their delegate. Where the DOC neither signs nor states its objection within 14 days of the Certificate being filed, the entity may apply to the Federal Court, which may order the signature.

21. Amendment of the Formation Instrument
(1) Unless otherwise provided, the formation instrument may be amended by a resolution of interest holders.
(2) An amendment does not affect an existing cause of action in favour of or against the entity, nor any pending legal action to which it is a party.
(3) An amendment that increases the personal liability of interest holders requires notice to be filed and given to each affected interest holder, and takes effect only against those who expressly accept it.
(4) Where an entity has more than one class of share or membership, an amendment that would:
(a) increase or decrease the number of authorised interests of a class;
(b) change the par value of a class; or
(c) alter the powers, preferences or special rights of a class so as to affect it adversely,
requires, in addition, a majority of the class affected, whether or not that class otherwise carries a vote.
(5) Subsection (4)(a) does not apply where the formation instrument provided otherwise before any interest of that class was issued.
(6) An amendment that forfeits, cancels, or compels the transfer of an interest already held takes effect against a holder only with that holder's consent, or on payment to them of fair value determined in the manner set out in section 54(2). This subsection may not be displaced by the formation instrument.
(7) The purpose of a foundation may be amended only in accordance with section 58.

22. Conversion
(1) An Incorporated Entity may convert into another form of Incorporated Entity by:
(a) a resolution of interest holders approving a Certificate of Conversion;
(b) filing that Certificate in its record; and
(c) the signature of the Secretary of the DOC or their delegate, to which section 20(6) applies.
(2) A Certificate of Conversion shall state the entity's current and new form, the formation instrument the entity will have on conversion, and the manner in which existing interests are converted into interests in the new form.
(3) On conversion the entity continues as the same legal person. Its property, rights, obligations, liabilities and legal actions are unaffected, and no liability of any person is released or impaired.
(4) A sole proprietorship may be converted into an Incorporated Entity by forming that entity and transferring the business to it. The owner remains liable for obligations incurred before the transfer.
(5) A foundation may not convert into another form, and no other form may convert into a foundation except with the approval of the Federal Court on an application showing that no person will obtain a benefit from the conversion that the purpose of the foundation would not allow.
(6) The DOC may refuse a conversion that would defeat a creditor, an existing order or an ongoing enforcement action.

PART V — GOVERNANCE COMMON TO ALL INCORPORATED ENTITIES

23. Resolutions

(1) This Part applies unless otherwise provided by law or by the formation instrument.
(2) Any director, manager, partner or interest holder may call for a resolution.
(3) A resolution must be posted where the persons entitled to vote can see it and vote on it. Posting in the entity's record always satisfies this requirement.
(4) A resolution must remain open for votes for 48 hours.
(5) Votes are counted by voting power, not by head.
(6) A resolution passes on a simple majority of the voting power cast, subject to quorum.
(7) In a foundation, the body entitled to vote is the board, and each director has one vote.

24. Quorum
(1) Quorum for a resolution is 50% of all voting power. An express abstention counts towards quorum.
(2) Where a resolution fails for want of quorum:
(a) the persons entitled to vote shall be notified;
(b) the resolution may be reposted after 72 hours, or sooner if a majority of total voting power waives that period; and
(c) for 10 days after the reposting, the quorum for that resolution is reduced to 25% of all voting power.
(3) The reduced quorum in subsection (2)(c) does not apply to a resolution under section 21, 22, 47, 48, 50, 52, 54, 65, 67 or 68, or to a resolution removing a director, manager or member of a Supervisory Board. Quorum for such a resolution may not be reduced below 50% of all voting power.
(4) A resolution under section 21, 22, 48, 50, 65, 67 or 68 must in any event carry a majority of all voting power, not merely of the voting power cast.
(5) Shares or memberships held by the entity itself, or by another entity it directly or indirectly controls, or by a Depositary Foundation whose board that entity appoints, neither vote nor count towards quorum.

25. Written Consent in Place of a Vote
(1) Any action that may be taken by resolution may instead be taken without a vote if persons holding the voting power that would be required to pass it consent in writing.
(2) The consent must identify the action and be recorded in a single filing or message thread that names each consenting person.
(3) The action takes effect when the last consent needed is given, or at any later time the consent states.
(4) Where the action is one for which a filing is required under section 16, the consent shall be filed in place of the resolution.
(5) Notice of an action taken by written consent shall be given without undue delay to each person entitled to vote who did not consent.

26. Notice
(1) Notice required by this Act is validly given by any durable and attributable means the recipient can reasonably be expected to see, including a filing in the entity's record, a message in a channel the recipient has access to, in game mail, or a forum message.
(2) A person may waive notice, before or after the event, and attendance or voting without objection waives any defect in notice.
(3) A defect in notice to a person does not invalidate an action unless the defect could have changed the outcome.

27. Directors, Managers and Officers
(1) The business and affairs of an Incorporated Entity are managed by or under the direction of its directors, managers or general partners, except as this Act or the formation instrument otherwise provides.
(2) Directors are elected and removed by resolution of interest holders. There is no limit on the number of seats.
(3) Where no first directors or managers are named in the formation instrument, the incorporators serve until directors or managers are appointed.
(4) The entity has such officers as the board or the managers require. Officers are appointed and removed at the pleasure of the board or the managers, and have the authority and duties the board or the managers give them.
(5) Unless otherwise restricted, the board or the managers may set the compensation of directors, managers and officers.
(6) A vacancy may be filled by the remaining directors or managers until the next resolution of interest holders.

28. Supervisory Boards
(1) A formation instrument may provide for a Supervisory Board, in which case the entity has a two tier structure consisting of a management board that manages the entity and a Supervisory Board that supervises the management board and the general course of the entity's affairs.
(2) A person may not serve on both boards at the same time.
(3) Unless otherwise provided, the Supervisory Board:
(a) is elected and removed by resolution of interest holders, or in a foundation is appointed in the manner its Certificate of Foundation provides;
(b) appoints, suspends and removes the members of the management board;
(c) may require any information from the management board, and has the access described in section 12(1);
(d) may approve or withhold approval of any decision the formation instrument reserves to it; and
(e) may not manage the entity or direct an individual transaction, except where the formation instrument expressly allows it.
(4) A decision taken without an approval required by subsection (3)(d) is voidable at the instance of the Supervisory Board, but the entity remains bound to a third party under section 10.
(5) Members of a Supervisory Board are agents for the purposes of section 9 and are treated as directors for the purposes of sections 11, 12, 82 and 83 and of Parts XI and XIX.
(6) An entity with a Supervisory Board shall list its members in the Entity Profile.

29. Annulment of Resolutions
(1) A resolution that is contrary to the formation instrument or the bylaws, or that was taken by a procedure materially departing from this Act, the formation instrument or the bylaws, is voidable.
(2) An interest holder, a director, a manager, a member of a Supervisory Board or the DOC may apply to the Federal Court to annul such a resolution, within 30 days of the resolution coming to the applicant's knowledge and in any event within 90 days of the resolution.
(3) The Court shall not annul a resolution where the defect could not have changed the outcome and caused no loss, and may instead order that the resolution be retaken.
(4) An annulment does not affect a right acquired in good faith by a third party before the annulment.
(5) A resolution whose content is contrary to a mandatory provision of this Act is void, and subsection (2) does not apply to it.

30. Deadlock
(1) Where the governing body or the interest holders of an Incorporated Entity are unable to act on a matter necessary to the continued operation of the entity for 30 consecutive days, any director, manager or interest holder may apply to the Federal Court.
(2) The Court may make any order it considers just, including ordering a vote, appointing a receiver, ordering a buyout of an interest at fair value, or ordering the winding up of the entity.

PART VI — GROUPS

31. Parent and Subsidiary

(1) A person is the parent of an entity where that person:
(a) holds a majority of the voting power in the entity;
(b) can appoint or remove a majority of its directors or managers; or
(c) exercises dominant influence over it, whether through contract, the formation instrument or in fact.
(2) An entity of which a person is the parent is a subsidiary of that person, and a parent together with all of its subsidiaries is a group.
(3) A subsidiary may not acquire or hold shares or memberships in its parent. An interest acquired contrary to this subsection carries no vote and no distribution, and shall be disposed of within 90 days.
(4) An entity that is a member of a group shall state that fact, and the identity of its parent, in its Entity Profile.

32. Instructions and Parent Liability
(1) A parent may give binding instructions to the directors or managers of a subsidiary where the formation instrument of the subsidiary, or an agreement filed in the subsidiary's record, permits it.
(2) Where a director or manager acts on an instruction validly given under subsection (1) and discloses the instruction to the subsidiary, that person is relieved of liability to the extent they so acted, and the parent is liable in their place.
(3) A parent that causes a subsidiary to act to the subsidiary's disadvantage shall compensate the subsidiary for that disadvantage within 90 days. Failing compensation, the subsidiary, an interest holder of the subsidiary, a creditor of the subsidiary while it is insolvent, or the DOC may recover it from the parent.
(4) A parent is liable for the debts of a subsidiary to the extent that it caused the subsidiary to become unable to pay them.

33. Group Interest
(1) A director or manager of an entity within a group does not breach section 9 by taking the interests of the group into account, provided that:
(a) the group is genuine and stable and the entity genuinely belongs to it;
(b) any disadvantage to the entity is balanced, over a reasonable period, by advantages arising from membership of the group; and
(c) the disadvantage does not exceed what the entity can bear and does not threaten its solvency.
(2) The director or manager bears the burden of establishing subsection (1).

PART VII — SOLE PROPRIETORSHIP

34. Sole Proprietorship

(1) A sole proprietorship is an in game company with no associated Incorporated Entity, and is a legal entity for the purposes of this Act.
(2) The assets and liabilities of a sole proprietorship are the assets and liabilities of its owner, and it has no liability or bankruptcy protection separate from its owner.
(3) The director of a sole proprietorship is at all times the owner of the in game company.
(4) A sole proprietorship requires no formation instrument, no record in the Company Register and no filings.
(5) The DOC shall disband a sole proprietorship within a reasonable time if the owner requests it.
(6) The DOC may disband an inactive sole proprietorship in accordance with section 84.

PART VIII — PARTNERSHIPS

35. General Partnership

(1) A general partnership exists where two or more persons carry on a business in common with a view to profit, whether or not they intend to form a partnership.
(2) A general partnership is a legal entity, but its partners are jointly and severally liable for its obligations without limit.
(3) Unless otherwise agreed:
(a) each partner has an equal share of profits and losses and an equal vote;
(b) each partner may bind the partnership in the ordinary course of its business;
(c) a decision in the ordinary course is taken by majority, and a decision outside the ordinary course, or one that amends the partnership agreement, requires unanimity; and
(d) a partner may withdraw on notice, and withdrawal does not dissolve the partnership if the remaining partners continue it.
(4) A general partnership need not file anything in the Company Register. A general partnership that files a Partnership Agreement is an Incorporated Entity for the purposes of Parts III and V, but subsection (2) continues to apply.

36. Limited Partnership
(1) A limited partnership is formed by filing a Partnership Agreement that identifies at least one general partner and at least one limited partner.
(2) A general partner manages the partnership and is liable for its obligations without limit.
(3) A limited partner is not liable for the obligations of the partnership beyond the amount that partner has contributed or agreed to contribute, and section 11 applies to a limited partner as it applies to a shareholder.
(4) A limited partner does not lose the protection of subsection (3) by voting on a matter reserved to limited partners, by advising the general partner, by serving as an agent of the partnership under a written mandate, or by exercising a right this Act gives them.
(5) A limited partner who holds themselves out to a counterparty as a general partner is liable to that counterparty as a general partner.

37. Limited Liability Partnership
(1) A limited liability partnership is formed by filing a Partnership Agreement stating that the partnership is a limited liability partnership.
(2) In a limited liability partnership, section 11 applies to every partner, and no partner is liable for the obligations of the partnership or for the acts or omissions of another partner solely by reason of being a partner.
(3) A partner remains liable for their own wrongful acts and for any obligation they have voluntarily assumed.

38. Partnership Interests and Records
(1) The Partnership Agreement is the formation instrument of a limited partnership and of a limited liability partnership.
(2) A limited partnership and a limited liability partnership shall keep a partner register in the Entity Profile listing each partner, their class, and whether they are a general or limited partner.
(3) The admission, withdrawal or removal of a partner must be filed, and takes effect on filing.
(4) Unless otherwise agreed, a partnership interest may not be transferred without the consent of the other partners, but the economic benefit of an interest may be assigned without consent and without conferring any voting or management right.

PART IX — LIMITED LIABILITY COMPANY

39. Formation and Membership

(1) The Certificate of Formation is the formation instrument of a limited liability company.
(2) An LLC has one or more members. Unless otherwise provided, members are admitted by unanimous vote of the existing members.
(3) Members with different characteristics form different member classes.
(4) Unless otherwise provided, each member has one vote and an equal share of distributions.
(5) An LLC may be managed by its members or by one or more managers. Unless otherwise provided, an LLC is managed by its members.

40. Managers
(1) Unless otherwise provided, a manager is designated by resolution of members.
(2) A manager is treated as a director for all purposes of this Act.
(3) Managers with different characteristics form different manager classes.

41. Member Register
(1) An LLC shall keep a member register in the Entity Profile recording each member, their class, and their membership interest.
(2) The register is rebuttable evidence of membership.
(3) Admission, resignation and removal of a member must be filed, stating the action, the member's name and their class, and takes effect on filing.

42. Series
(1) A Certificate of Formation may provide for the establishment of one or more series of members, managers, interests or assets.
(2) Where the Certificate of Formation so provides and the records of the LLC account for the assets and liabilities of each series separately, the debts, obligations and liabilities of a series are enforceable only against the assets of that series and not against the assets of the LLC generally or of any other series.
(3) The Entity Profile shall list each series and state that the LLC has series liability separation.
(4) Subsection (2) does not apply in favour of a series in respect of an obligation incurred before the series was listed in the Entity Profile, nor where the assets of the series have been commingled with those of the LLC or another series.

PART X — CORPORATION

43. Certificate of Incorporation

(1) The Certificate of Incorporation is the formation instrument of a corporation.
(2) In addition to section 18(2), the Certificate of Incorporation shall state, for each class of share:
(a) the name of the class, where there is more than one;
(b) the number of shares authorised; and
(c) the par value per share.
(3) A corporation formed on the Standard Form is taken to have a single class of ordinary shares carrying one vote each and having no par value, in the number stated in its formation filing.

44. Shares
(1) A corporation shall at all times have at least one outstanding share, and the outstanding shares must, singly or together, carry full voting power. An act contrary to this subsection is void.
(2) There are no fractional shares.
(3) Shares with different characteristics form different classes.
(4) Authorised shares that are not outstanding are held by the corporation.
(5) A shareholder is liable for any part of the price they agreed to pay for their shares that has not been paid up. That liability may not exceed the agreed subscription price, and where the shares have no par value or the agreed price is not recorded, the liability is nil.
(6) Shares held by the corporation, or by another Incorporated Entity it directly or indirectly controls, neither vote nor count towards quorum and carry no right to a distribution.
(7) Shares may not be issued or held to bearer. Every share must be registered to a named holder, and a bearer instrument purporting to represent shares is void.

45. Share Register
(1) A corporation shall keep a share register in the Entity Profile recording all shares.
(2) An entry shall state the class where there is more than one, the number of shares, and the name of the holder or, for shares represented by a certificate, the serial number of the certificate.
(3) Where shares are held through a registered exchange or a Depositary Foundation, that exchange or foundation shall be listed as holder and the register it maintains is incorporated by reference.
(4) The share register is rebuttable evidence of ownership.
(5) A transfer of registered shares must be filed under section 16(1)(e), stating the class, the number of shares, the transferor and the transferee.

46. Share Certificates
(1) A corporation may issue share certificates unless its Certificate of Incorporation provides otherwise.
(2) A share certificate must:
(a) be an in game written book;
(b) be titled with the registered name of the corporation, or a recognisable abbreviation;
(c) be signed by a director at the time of issue; and
(d) state the full name of the corporation, the unique serial number of the certificate, the class of shares, the number of shares and the name of the shareholder.
(3) The creation or destruction of a share certificate, and the corresponding change to the share register, must be filed without undue delay, stating the class, the number of shares and the serial number.
(4) This section does not apply to a purely decorative and non binding certificate.

PART XI — CAPITAL AND CREDITOR PROTECTION

47. Distributions

(1) A corporation may make a distribution to its shareholders only out of distributable reserves.
(2) No distribution may be made if, after giving effect to it, the corporation would be unable to pay its debts as they fall due or its liabilities would exceed its assets.
(3) A director who approves a distribution contrary to this section is personally liable to the corporation for the amount by which the distribution exceeded what was permitted, unless the director establishes that they had reasonable grounds to believe the distribution was permitted after making reasonable inquiry.
(4) A shareholder who received a distribution knowing that it contravened this section shall repay it to the corporation.
(5) This section applies, with the necessary changes, to a distribution by an LLC, a cooperative, a limited partnership or a limited liability partnership to its members or partners.
(6) This section does not apply to a payment of reasonable compensation for services actually rendered, to the repayment of a debt owed to an interest holder on its ordinary terms, or to a distribution made in the course of a winding up under Part XVIII.

48. Reduction of Capital
(1) A corporation may reduce its issued capital, cancel issued shares or return capital to shareholders by a resolution of shareholders, which must be filed.
(2) The filing must state the reduction, the amount to be returned if any, and that a creditor may object within 14 days.
(3) A creditor whose debt is due, or is contingent and reasonably certain to become due, may within that period require the corporation to pay the debt or give security for it.
(4) The reduction does not take effect as against an objecting creditor until the debt is paid or secured, or the Federal Court determines that the creditor is adequately protected.
(5) The DOC may extend the objection period to 30 days for a licensed financial institution or a Public Company.

49. Serious Loss of Capital
(1) Where the net assets of a corporation fall below half of its issued capital, its directors shall, within 14 days of becoming aware of that fact, file notice of it and put to the shareholders a resolution on whether to recapitalise the corporation, to reduce its capital, to dissolve it, or to continue and on what basis.
(2) A failure to comply with subsection (1) is a ground for disqualification under section 83 and for action by the DOC under Part XXI.
(3) This section does not apply to a corporation formed on the Standard Form with total assets below $100,000, unless it is a licensed financial institution or a Public Company.

50. Financial Assistance
(1) A corporation may not give financial assistance, whether by loan, guarantee, security, indemnity, gift or the release of an obligation, for the purpose of an acquisition of its own shares or of shares in its parent.
(2) Subsection (1) does not apply where the assistance is given out of distributable reserves, is approved by a resolution of shareholders passed by two thirds of the voting power cast, and does not render the corporation unable to pay its debts as they fall due.
(3) A transaction contravening this section is voidable at the instance of the corporation, a creditor or the DOC, and the directors who approved it are jointly and severally liable to the corporation for any resulting loss.

51. Acquisition of Own Shares
(1) A corporation may acquire its own shares only out of distributable reserves and only where section 44(1) continues to be satisfied after the acquisition.
(2) An acquisition contrary to this section is void, and the directors who approved it are jointly and severally liable to restore the corporation to the position it would have been in.

PART XII — SHAREHOLDER AND MINORITY RIGHTS

52. Pre-emption Rights

(1) Where a corporation proposes to issue shares of a class for cash, it shall first offer them to the existing holders of that class, in proportion to their holdings and on the same terms, and shall keep the offer open for at least 48 hours.
(2) Pre-emption rights may be disapplied:
(a) for a particular issue, by a resolution of shareholders passed by two thirds of the voting power cast; or
(b) generally, by the formation instrument.
(3) This section does not apply to shares issued:
(a) for consideration other than cash;
(b) to agents or employees under an incentive plan approved by resolution;
(c) on the conversion or exercise of an instrument whose issue was itself subject to this section; or
(d) by a Public Company through the Stock Exchange on which it is listed.
(4) An issue made in contravention of this section is voidable at the instance of an excluded shareholder, who may alternatively require the corporation to place them in the position they would have occupied had the offer been made.

53. Mandatory Offer on Acquiring Control
(1) A person who, alone or acting in concert with others, comes to hold shares carrying 30% or more of the voting power of a Public Company shall, within 7 days, offer to acquire all remaining shares of that class at a price not lower than the highest price that person paid for a share of that class in the preceding 90 days.
(2) Until the offer is made, the voting power held by that person above the 30% threshold is suspended.
(3) The DOC may waive subsection (1) where:
(a) the holders of a majority of the shares not held by that person or its concert parties approve the waiver by resolution; or
(b) the threshold was crossed involuntarily, and the person reduces their holding below it within 14 days.
(4) This section applies only to Public Companies.

54. Squeeze-out
(1) A person who holds shares carrying 90% or more of the voting power of a class, and 90% or more of the issued shares of that class, may require the remaining holders of that class to sell their shares at fair value, by a notice filed in the corporation's record and given to each remaining holder.
(2) A remaining holder may, within 14 days of the notice, apply to the Federal Court to determine fair value, and the Court's determination binds all remaining holders.
(3) On payment or tender of the price, the shares transfer by operation of this section and the corporation shall update the share register.

55. Sell-out
(1) Where a person reaches the threshold in section 54(1), any remaining holder of that class may, within 90 days, require that person to purchase their shares at fair value.
(2) Section 54(2) applies to the determination of fair value.

PART XIII — COOPERATIVE

56. Cooperative

(1) A cooperative is an Incorporated Entity owned and controlled by its members, formed by filing a Certificate of Cooperation.
(2) Unless otherwise provided, each member of a cooperative has one vote regardless of the size of their contribution, and this default may not be displaced so as to give any member or related group more than 40% of total voting power.
(3) A cooperative shall elect its governing body democratically from among its members.
(4) Surplus of a cooperative may be retained, reinvested, or distributed to members in proportion to their use of the cooperative rather than their capital contribution.
(5) Part IX applies to a cooperative as it applies to a member managed LLC, so far as it is consistent with this Part.
(6) A credit union licensed under the Commercial Standards Act shall be formed as a cooperative or as a non-profit.

PART XIV — FOUNDATION

57. Foundation

(1) A foundation is formed by filing a Certificate of Foundation, which shall state:
(a) the purpose of the foundation, stated with enough particularity that a court can determine whether an act furthers it;
(b) the initial endowment, which may be nil;
(c) the first directors and the manner in which their successors are appointed and removed; and
(d) the destination of the net assets on dissolution.
(2) A foundation has no members, no shares and no interest holders, and no person holds an ownership interest in it.
(3) The assets of a foundation are bound to its purpose, and a founder retains no claim to them. They are not available to the creditors of its founder, except that an endowment or transfer to the foundation may be set aside on the application of a creditor of the transferor, and the value recovered, where the transfer:
(a) left the transferor unable to pay their debts as they fell due, or was made while they were unable to do so;
(b) was made within 12 months before the debt claimed arose or became due; or
(c) was made with intent to hinder, delay or defeat a creditor, an order or an enforcement action.
(d) submit financial reports on a reasonable schedule set by the DOC, being no more often than monthly.
(4) A foundation may carry on business and hold interests in other entities.
(5) A foundation may not make a distribution, directly or indirectly, to its founder, its directors, or any person exercising control over it, other than:
(a) reasonable compensation for services actually rendered and reimbursement of expenses actually incurred; and
(b) a distribution to that person as a beneficiary, where the Certificate of Foundation identifies them as a beneficiary and the distribution furthers the stated purpose.
(6) A foundation may make distributions in furtherance of its purpose, including to beneficiaries identified in or determined in the manner set out in the Certificate of Foundation.

58. Governance and Purpose
(1) A foundation is governed by its board, which holds the powers this Act gives to directors and to interest holders.
(2) A foundation may establish a Supervisory Board under section 28, and shall do so where its Certificate of Foundation requires it.
(3) The purpose of a foundation may be amended only in the manner its Certificate of Foundation provides.
(4) Where the purpose has become impossible, unlawful, or so impracticable that pursuing it wastes the foundation's assets, the board, a beneficiary or the DOC may apply to the Federal Court, which may amend the purpose to the lawful purpose nearest to the original intention, or order the foundation dissolved.
(5) The DOC may apply to the Federal Court to remove a director of a foundation who acts contrary to its purpose or derives an improper benefit from it, and the Court may appoint a replacement.

59. Depositary Foundations and Depositary Receipts
(1) A foundation whose purpose is to hold shares or membership interests and to issue Depositary Receipts against them is a Depositary Foundation.
(2) A Depositary Foundation is the registered holder of the underlying interests and exercises all voting power attaching to them. The holder of a Depositary Receipt is entitled to the distributions, proceeds and other economic benefit of the underlying interest, and to no vote.
(3) The terms of administration must be filed in the record of the Depositary Foundation and in the record of the issuer of the underlying interests, and must state:
(a) how Depositary Receipts are transferred;
(b) whether and on what conditions a Depositary Receipt may be exchanged for the underlying interest; and
(c) how the board of the Depositary Foundation is appointed and removed.
(4) A Depositary Foundation shall keep a register of receipt holders in its Entity Profile, and section 12(4) applies to it.
(5) A Depositary Foundation owes a duty to the holders of its Depositary Receipts to exercise the voting power it holds in the interests of the issuer and, so far as consistent with those interests, of the receipt holders. Unless the terms of administration provide otherwise, the board shall consult receipt holders before voting on a merger, consolidation, division, dissolution, or an amendment that would adversely affect the receipts.
(6) A Depositary Receipt is a financial product for the purposes of the Commercial Standards Act, and its offer to the public is subject to that Act.
(7) Notwithstanding the terms of administration, the holders of Depositary Receipts:
(a) may, by a majority of the receipts of a class, remove and replace the board of the Depositary Foundation;
(b) have the information rights of an interest holder under section 12(2) in respect of both the foundation and the issuer;
(c) have standing under sections 9(5) and 29(2); and
(d) may exchange their receipts for the underlying interests on 30 days notice, unless the terms of administration exclude exchange and the foundation holds interests in a Public Company, in which case the exclusion is valid for no more than 2 years at a time and must be renewed by a majority of the receipts.
(8) For the purposes of sections 24(5), 31(3), 44(6), 53 and 54, interests held by a Depositary Foundation are treated as held by the person who appoints or may remove its board.
(9) A change in the register of receipt holders must be filed, and section 16(2) applies to those filings.

60. Anti-abuse
(1) A foundation may not be used to defeat a creditor, to evade an existing obligation or an order, or to conceal the control of an entity.
(2) Where a founder or another person retains the practical ability to direct the assets of a foundation for their own benefit, those assets are treated as that person's assets for the purposes of enforcement against them, and section 11(6) applies.
(3) For the purposes of subsection (2), a person is presumed to retain that ability where they:
(a) are named as a beneficiary of the foundation;
(b) may appoint or remove a director of the foundation, whether directly or through another person; or
(c) may amend the purpose of the foundation or direct its dissolution.
(4) The presumption in subsection (3) may be rebutted by evidence that the foundation is in fact administered independently of that person.
(5) The DOC, or a creditor of the person concerned, may apply to the Federal Court for a declaration under subsection (2).
(6) An amendment to the purpose of a foundation that confers a benefit on its founder, a director, or a person exercising control over it requires the approval of the Federal Court.

PART XV — NON-PROFIT

61. Non-profit

(1) A non-profit is a member based LLC, a cooperative or a foundation that states a clear purpose in its formation instrument and holds itself out as a non-profit.
(2) A non-profit must keep its non-profit character at all times, and accordingly:
(a) revenue may not be distributed to its members;
(b) compensation must be reasonable; and
(c) transactions with members and related parties must be at arm's length.
(3) The DOC may grant a non-profit an exemption from taxation, and a non-profit holding such an exemption shall:
(a) keep transaction and accounting records; and
(b) submit financial reports on a reasonable schedule set by the DOC, being no more often than monthly.
(4) The DOC may withdraw the exemption for misconduct or non-compliance.
(5) On a voluntary winding up, any net surplus of a non-profit shall be transferred to the government, transferred to another registered non-profit, or returned to its donors up to the amount each donated.

PART XVI — GOVERNMENTAL ENTITY

62. Formation and Existence

(1) A governmental entity is formed by executive order, law, town bylaw or town constitution, and exists from the enactment of that instrument until its dissolution.
(2) Governmental entities are exempt from all taxes except as expressly provided by law.
(3) Where not otherwise defined, the directors of a governmental entity are:
(a) each person in a body of equal persons, notwithstanding that a chair or equivalent is elected or appointed from that body; or
(b) failing that, the most senior person leading the entity.
(4) For the avoidance of doubt, the existing governmental entities are:
(a) the executive departments, whose director is the Secretary of the department;
(b) towns, and town departments and other entities created by town bylaw or constitution;
(c) the Federal Reserve Bank, whose directors are all members of the FRB Board;
(d) the Judiciary, which is a single governmental entity whose directors are the justices of the Supreme Court;
(e) the House of Representatives, whose director is the Speaker;
(f) the Senate, whose director is the President of the Senate;
(g) Congress, whose directors are the presiding officers of both chambers; and
(h) any other entity created by an avenue listed in subsection (1).
(5) A governmental entity that carries on commercial activity in competition with private entities is, in respect of that activity, subject to Parts II, III and XIX of this Act and to taxation on that activity, and shall maintain a record in the Company Register. Service on such an entity may be effected on any of its directors under subsection (3).

63. Legal Representation
(1) The Department of Justice is the legal representative of the executive departments.
(2) Any other governmental entity may request lawyers from the Department of Justice.
(a) The Department of Justice may reject the request only for an extraordinary reason, and extreme overload on the Department is such a reason.
(b) In representing a governmental entity that is not an executive department, the Department shall give special deference to the wishes of that entity rather than substituting its own judgement.
(c) A governmental entity that is not an executive department may seek outside counsel.
(3) Executive departments may not sue each other.

64. Receivership of Governmental Entities
(1) A governmental entity may be placed in receivership only in respect of its financial affairs, and any receivership over a governmental entity is limited accordingly.

PART XVII — MERGER, CONSOLIDATION AND DIVISION

65. Merger and Consolidation

(1) Two or more Incorporated Entities may merge into one of them, or consolidate into a new entity, as provided in this Part, whether or not they are of the same form.
(2) A Certificate of Merger or Consolidation shall state:
(a) the name of each constituent entity, any former name under which it was formed, and the name of the surviving or consolidated entity;
(b) the terms of the merger or consolidation, including how the interests of each constituent entity are converted into interests, securities, cash or other consideration;
(c) in the case of a merger, any amendment to the formation instrument of the surviving entity;
(d) in the case of a consolidation, the formation instrument of the consolidated entity; and
(e) any other provision the constituent entities consider necessary or desirable.
(3) A Certificate of Merger or Consolidation must be approved by a resolution of the interest holders of each constituent entity and filed in the record of each constituent entity.
(4) The Certificate takes effect on the signature of the Secretary of the DOC or their delegate, given on verification that the Certificate is lawful, and section 20(5) applies to that signature.
(5) A foundation may merge or consolidate only with another foundation, and only where the purpose of the surviving or consolidated foundation is substantially the same as that of each constituent foundation.

66. Effect of Merger or Consolidation
(1) On a merger or consolidation taking effect:
(a) the surviving or consolidated entity has all the rights, privileges, immunities, powers and purposes of each constituent entity;
(b) all property, rights, causes of action and other assets of each constituent entity vest in it without further act;
(c) it assumes and is liable for all the liabilities, obligations and penalties of each constituent entity;
(d) no liability, claim or demand against a constituent entity or against any of its interest holders or agents is released or impaired;
(e) no legal action pending by or against a constituent entity or its interest holders or agents is abated, and the surviving or consolidated entity may be substituted as a party;
(f) in a merger, the formation instrument of the surviving entity is amended to the extent set out in the Certificate;
(g) in a consolidation, the formation instrument set out in the Certificate becomes the formation instrument of the consolidated entity; and
(h) unless the Certificate provides otherwise, each constituent entity that is not the surviving or consolidated entity ceases to exist and is dissolved without further winding up.

67. Division
(1) An Incorporated Entity may divide into two or more entities by a Certificate of Division approved and filed in the same manner as a Certificate of Merger.
(2) A Certificate of Division shall allocate the assets, liabilities and legal actions of the dividing entity among the resulting entities.
(3) An allocation of a liability does not bind a creditor who has not consented to it, and each resulting entity is jointly and severally liable for a liability of the dividing entity incurred before the division unless that creditor consented.
(4) The DOC may refuse to sign a Certificate of Division that would leave any resulting entity unable to pay its debts.

PART XVIII — DISSOLUTION AND WINDING UP

68. Dissolution

(1) Unless otherwise provided:
(a) the directors or managers may adopt and file a resolution advising dissolution; and
(b) the dissolution must then be approved by a resolution of interest holders passed by at least a simple majority, which must be filed.
(2) A dissolution resolution may set out the process of winding up, and that process is binding, but it may not override the formation instrument or the bylaws.
(3) On the approval of a dissolution the entity shall wind up its affairs and may carry on only such business as is necessary to do so.

69. Notice to Creditors
(1) On the filing of an approved dissolution resolution, the DOC shall publicly announce the winding up in the government announcements channel, naming the entity and its directors, and requesting any counterparty, interest holder, creditor or other interested person to contact the entity.
(2) The entity shall give direct notice of the winding up to every creditor known to it.
(3) A person who does not contact the entity, its directors or the DOC within 14 days of the announcement may not thereafter enforce their claim against the assets distributed in the winding up. The claim itself is not extinguished, and remains enforceable against any person liable for it under section 11, section 73, or subsection (6).
(4) Subsection (3) does not apply to a creditor who was entitled to direct notice under subsection (2) and did not receive it.
(5) A voluntary dissolution may not be commenced while the entity is insolvent. Section 88(3) applies.
(6) An interest holder who received a distribution in a winding up shall repay it, up to the amount received, to satisfy a claim that was not paid because the assets had already been distributed, where the claim is brought within 2 years of the Certificate of Dissolution being signed. A director who approved the distribution knowing of the claim is jointly liable.

70. Winding Up
(1) Winding up consists of:
(a) ending all contracts;
(b) paying all creditors and debts;
(c) concluding all legal actions; and
(d) distributing the remaining assets in accordance with the dissolution resolution and the formation instrument, and by default:
(i) in a corporation, among shareholders in proportion to their shares;
(ii) in an LLC, cooperative or partnership, among members or partners in proportion to their interests, or equally if no proportion is defined;
(iii) in a non-profit, in accordance with section 61(5); and
(iv) in a foundation, to the destination stated in its Certificate of Foundation, or failing that to another entity with a substantially similar purpose.
(2) A distribution to an interest holder may not be made until all creditors have been paid or provided for.

71. Certificate of Dissolution
(1) A fully wound up entity shall file a Certificate of Dissolution.
(2) The Secretary of the DOC or their delegate shall sign the Certificate after verifying that the entity has been fully wound up, or shall state in the record what remains outstanding.
(3) The entity ceases to exist on the signature of the Certificate being filed.
(4) Where the DOC neither signs the Certificate nor states what remains outstanding within 14 days of filing, the entity may apply to the Federal Court, which may order the signature or dissolve the entity directly.

PART XIX — INSOLVENCY DUTIES

72. Duty on Insolvency

(1) An entity is insolvent where it is unable to pay its debts as they fall due, or where its liabilities exceed its assets.
(2) Where the directors or managers of an Incorporated Entity know, or ought reasonably to know, that it is insolvent, they shall within 7 days:
(a) restore its solvency;
(b) file a petition under the Bankruptcy Act; or
(c) apply to the Federal Court for the appointment of a receiver.
(3) During that period, and until one of those steps is taken, they shall not cause the entity to incur a new obligation or make a payment other than one necessary to preserve its assets, to minimise the loss to its creditors as a whole, or to give effect in good faith to a genuine attempt to restore solvency under subsection (2)(a).
(4) Notice that the duty in subsection (2) has arisen must be filed, and a director may not be sanctioned under Part XXI for making that filing in good faith.

73. Wrongful Trading
(1) A director or manager who contravenes section 72 is personally liable to the entity for the amount by which its net deficiency increased between the day the duty arose and the day it was complied with.
(2) It is a defence that the person took every reasonable step to minimise the loss to the entity's creditors as a whole.
(3) A claim under this section may be brought by the entity, a receiver, a creditor or the DOC, and the Federal Court may in addition disqualify the person under section 83.
(4) A member of a Supervisory Board is liable under this section only where they knew of the insolvency and failed to act on it.

74. Insolvent Transactions
(1) The DOC, or a creditor owed a debt that is due and unpaid, may apply to the Federal Court to wind up and dissolve an Incorporated Entity that is insolvent or has abandoned its business, and the Court may appoint a receiver to conduct the winding up.
(2) A transfer, distribution or payment made by an Incorporated Entity to an insider while insolvent, or that leaves the entity unable to pay its debts, may be set aside by the Federal Court and recovered for the benefit of creditors.
(3) A payment or transfer made to a creditor while the entity was insolvent, or within 30 days before it became insolvent, that put that creditor in a better position than they would have occupied in a winding up, may be set aside on the application of a receiver, another creditor or the DOC, unless the creditor gave new value for it in good faith.
(4) This section does not apply where a bankruptcy case is on foot, in which case Part VII of the Bankruptcy Act applies. A recovery under this section is credited against any recovery for the same transfer under that Act, and no person may be made to restore the same value twice.

PART XX — RECEIVERSHIP

75. Receivership

(1) A legal entity in receivership is led by a receiver.
(2) A legal entity may be placed into receivership only by a process defined by law. A court may place a legal entity into receivership to enforce a court order.
(3) The DOC may apply to the Federal Court to place a legal entity into receivership where the entity is insolvent, is being used to commit fraud, or persistently and seriously violates the law. Where creditor or customer funds are at immediate risk, the DOC may impose an interim receivership for no longer than 72 hours pending the decision of the Court.
(a) The application to the Court must be filed no later than the moment the interim receivership begins.
(b) An interim receiver may not dispose of an asset outside the ordinary course of the entity's business without the approval of the Court, and a disposal made contrary to this paragraph is voidable.
(c) The DOC may not impose a further interim receivership over the same entity within 30 days, except on a materially different ground.
(4) A receiver has the power:
(a) of the directors, managers, officers and interest holders, cumulatively, and without the restrictions of the formation instrument;
(b) to control all assets and liabilities;
(c) to suspend or restrict the voting power of any interest holder;
(d) to suspend or restrict any direct or indirect control or voting power over the entity arising from contract, equity, debt or law; and
(e) to suspend or restrict any power of a director, manager or officer.
(5) A receiver may not increase the limit of personal liability assumed by any person, nor change the payout resulting from a winding up.
(6) A receiver is immune from civil liability for acts done in good faith in the exercise of their powers, except where the receiver commits a criminal offence or acts outside the scope of their authority.
(7) A receiver owes no fiduciary duty to interest holders, agents, creditors or other stakeholders. Their duties are owed exclusively to the appointing court or authority and to the proper administration of the receivership, and their acts are not challengeable for breach of fiduciary duty.
(8) A receiver appointed under the Commercial Standards Act over an operation carrying on regulated financial activity, together with the relevant assets of its operators, holds the powers and immunities in this section whether or not the operation is a legal entity.

PART XXI — REGULATION AND ENFORCEMENT

76. Rulemaking

(1) The DOC may make rules regulating:
(a) the procedure and format of filings in the Company Register, and the creation of a filing obligation or a periodic return;
(b) the naming of entities;
(c) the content of the Standard Form and of the Entity Profile;
(d) the records and registers an entity must keep;
(e) a minimum capital, asset or reserve threshold for a class of entity;
(f) the reporting of tax exempt non-profits and of foundations; and
(g) any other matter this Act assigns to it.
(2) A rule must serve a legitimate governmental purpose and be reasonably tailored to achieve it.
(3) A rule that creates a filing obligation, a periodic return or a minimum threshold shall:
(a) state the burden it imposes and the purpose that burden serves;
(b) exempt entities formed on the Standard Form with total assets below $100,000, unless they are licensed financial institutions, Public Companies or foundations; and
(c) not require information the entity has already filed, or that is already available to the DOC.
(4) A rule takes effect on publication.
(5) Congress may disallow a rule by resolution of both chambers, and a rule so disallowed ceases to have effect and may not be remade in substantially the same terms in the same Congress.

77. Administrative Sanctions
(1) An administrative sanction under this Act must be coercive and strictly not punitive.
(2) To compel compliance with this Act the DOC may:
(a) issue public warnings, censures and reprimands;
(b) impose a default penalty for a continuing failure to make a filing this Act or a rule requires, not exceeding $500 per day and not exceeding $10,000 in total for any one failure; and
(c) pursue civil administrative enforcement against persons and legal entities.
(3) A warning must be given at least 24 hours before a sanction is assessed, unless there is a clear and justified reason to act sooner.
(a) The warning must cite this section, state the matter concerned and set out the steps to remedy it.
(b) A warning is given per matter, not per offence or per sanction.
(4) A default penalty stops accruing when the failure is remedied, and the DOC may waive it in whole or in part where the failure caused no loss.
(5) Nothing in this section prevents transparent communication to the public.
(6) The sanction powers in this section extend to the enforcement of the Commercial Standards Act.

78. Investigation and Inspectors
(1) The DOC may require a legal entity or its agents to produce books, records, filings and information relevant to an investigation of compliance with this Act.
(2) The DOC may appoint one or more inspectors to investigate the affairs, ownership, control or management of a legal entity, and an inspector may:
(a) require the production of any record of the entity or of a person connected with it;
(b) require a director, manager, officer, interest holder or former holder of any of those positions to answer questions relating to the investigation; and
(c) require the entity to explain any transaction, holding or arrangement.
(3) An inspector shall report to the Secretary of the DOC, and the report is admissible as evidence of the facts it states in any proceeding under this Act, subject to rebuttal.
(4) Where the investigation establishes a contravention, the Federal Court may order the entity or a person responsible for the contravention to bear the costs of the investigation.
(5) Failure to comply with this section permits the DOC to draw adverse inferences and to pursue administrative sanctions.

79. Binding Determinations and Guidance
(1) A person may apply to the DOC for a determination of how this Act applies to a proposed act, structure or transaction.
(2) The DOC may issue a binding determination, which it may make subject to conditions, and on which the applicant may rely while it remains in force. The DOC may vary or revoke a determination with effect only from the date of variation or revocation.
(3) The DOC may publish general guidance on the operation of this Act. Guidance is not binding, but good faith reliance on published guidance is a defence to an administrative sanction under section 77.

80. Strike Off and Restoration
(1) The DOC may strike an Incorporated Entity from the Company Register where the entity:
(a) has had no director, manager or general partner able and willing to act for 30 consecutive days;
(b) has failed to respond to two notices served at intervals of not less than 7 days; or
(c) is persistently inactive within the meaning of section 84.
(2) Before striking an entity off, the DOC shall give 14 days notice, filed in the entity's record and given to its interest holders so far as they are known.
(3) On being struck off, the entity ceases to exist, and its remaining assets vest in the Government subject to restoration under subsection (4). The liability of a director, manager, interest holder or other person is unaffected by the strike off.
(4) A person with an interest in the entity, including a creditor, may apply:
(a) to the DOC within 3 months of the strike off; or
(b) to the Federal Court within 1 years of the strike off,
to restore the entity, and on restoration the entity is treated as having continued in existence throughout.
(5) The DOC shall restore an entity on application under subsection (4)(a) where the ground for the strike off has been remedied or where restoration is necessary to allow a creditor to pursue a claim.

81. Appointment of Interim Directors
(1) Where an Incorporated Entity has no director, manager or general partner able and willing to act, and its affairs require action to protect creditors, customers or interest holders, the DOC may apply to the Federal Court to appoint a person to act as a director of the entity for a limited purpose and period.
(2) Where creditor or customer funds are at immediate risk, the DOC may make such an appointment directly for a period of no more than 14 days, pending an application to the Court.
(3) A person appointed under this section is entitled to reasonable remuneration from the assets of the entity and holds the immunities of a receiver under section 75(6).
(4) An appointment under this section shall be filed in the entity's record.

82. Standing of the Department
(1) The DOC may:
(a) bring a claim on behalf of an Incorporated Entity for breach of fiduciary duty under section 9, for wrongful trading under section 73, or under Part XI, where the entity has failed to do so;
(b) apply to annul a resolution under section 29;
(c) apply for personal liability under section 11(6) or a declaration under section 60(2);
(d) apply to wind up an entity under section 74; and
(e) intervene in any proceeding under this Act.
(2) A sum recovered in a claim brought under subsection (1)(a) belongs to the entity, less the DOC's costs of the claim.

83. Disqualification
(1) The DOC may apply to the Federal Court to disqualify a person from acting as, or forming, a director, manager, general partner or officer of any legal entity for a specified period, where the person has committed fraud, persistently breached this Act, contravened Part XI or Part XIX, or was an agent of an entity wound up for misconduct or insolvency.
(2) A disqualified person who acts in a prohibited capacity contravenes this Act.

84. Inactive Entities
(1) The DOC may disband an inactive sole proprietorship.
(a) Five days notice must be given to the owner by in game mail before disbandment.
(b) The proprietorship shall be liquidated and the net proceeds transferred to the owner.
(c) No notice is required where the owner has been pruned under the Taxation Act.
(2) The DOC may place a persistently inactive Incorporated Entity into receivership, wind it up and dissolve it, or strike it off under section 80.
(a) Fourteen days notice must be given to its interest holders by Discord, in game mail or forum message, as applicable, and filed in the entity's record.
(b) Section 80(4) applies to an entity dissolved or struck off under this subsection as it applies to a strike off.
(3) Inactivity requirements set by the DOC must be made as rules under section 76, must be clear and objective, must not include playtime, must serve a compelling governmental purpose and must be reasonably tailored to achieving it.

PART XXII — TRANSITION AND GENERAL

85. Continuity

(1) Every entity existing under the repealed Legal Entity Act continues to exist under this Act as an entity of the corresponding form.
(2) An operating agreement or set of bylaws existing under the repealed Act remains in force and is treated as delegated to under section 18(4).
(3) Nothing in this Act affects an existing legal action or a liability already accrued.
(4) A filing validly made under the repealed Act is a valid filing under this Act.
(5) An entity is not required to refile, restate or reformat anything by reason of this Act alone, except that every Incorporated Entity shall post a compliant Entity Profile under section 17 within 30 days of the enactment of this Act.

86. Transition for New Obligations
(1) A filing obligation imposed by the repealed Act that is not carried into section 16 ceases on the enactment of this Act, and no sanction may be assessed for a failure to make such a filing occurring before that date where the failure caused no loss.
(2) Parts XI, XII and XIX apply to acts and omissions occurring on or after the enactment of this Act.
(3) An entity that, on the enactment of this Act, holds shares in its parent contrary to section 31(3) has 90 days to dispose of them.
(4) Section 53 does not apply to a holding of 30% or more acquired before the enactment of this Act, but does apply to any further acquisition by that person.

87. Relationship to Other Acts
(1) This Act is to be read with the Commercial Standards Act, which governs the licensing, conduct and taxation of financial institutions and the regulation of trade, employment and advertising.
(2) Where a person carries on regulated financial activity, the requirements of the Redmont Commerce and Finance Act apply in addition to this Act.
(3) A reference in any enactment to the Legal Entity Act is read as a reference to this Act.

88. Relationship to the Bankruptcy Act
(1) The Bankruptcy Act governs the insolvency of a person, the administration of an estate, the priority of claims, and the avoidance and clawback of transfers. This Act governs the constitution, governance and winding up of legal entities. Where the two Acts address the same matter, the Bankruptcy Act prevails to the extent of any inconsistency.
(2) Where a bankruptcy case is on foot in respect of an Incorporated Entity:
(a) the Trustee appointed under that Act serves as receiver under Part XX of this Act;
(b) the winding up is conducted under Part XVIII of this Act as modified by the priority rules in Part VI of the Bankruptcy Act, which displace section 70(1)(d);
(c) sections 72 to 74 of this Act do not apply, and the avoidance and clawback provisions in Part VII of the Bankruptcy Act apply in their place; and
(d) the Certificate of Dissolution is filed under section 71 of this Act.
(3) An Incorporated Entity that is insolvent may not commence a voluntary dissolution under Part XVIII. It shall proceed under the Bankruptcy Act, and a dissolution commenced while the entity was insolvent is voidable on the application of a creditor, a Trustee or the DOC.
(4) Sections 72 and 73 impose duties additional to the Bankruptcy Act. Compliance with section 72(2) by filing under the Bankruptcy Act discharges those duties.

89. Severability
(1) If any provision of this Act is held invalid or unenforceable, the remainder continues in full force and effect.
 

CONGRESS OF THE
COMMONWEALTH OF REDMONT

​


A BILL TO
Restate the Standards of Commerce
​


The people of the Commonwealth of Redmont, through their elected Representatives in the Congress and the force of law ordained to that Congress by the people through the constitution, do hereby enact the following provisions into law:
​
PART I — PRELIMINARIES

1. Short Title and Enactment

(1) This Act may be cited as the 'Redmont Commerce and Finance Act' or the 'RCFA'.
(2) This Act shall be enacted immediately upon its signage.
(3) This Act has been authored by President Theory Fontaine, Commerce Secretary Planke Fontaine, and FRB Governer Coshjlose.
(4) This Act has been co-sponsored by Senator ElegantAlly.
(5) This Act repeals and replaces the following acts:
(a) Commercial Standards Act
(b) Financial Institutions Enforcement Act
(c) Banking Income Tax Act
(6) This Act amends the following acts:
(a) Taxation Act
(b) Criminal Code Act
(c) Redmont Civil Code Act
(d) Bankruptcy Act
(7) This Act is to be read with the Legal Entity Act, which governs the formation, governance and dissolution of legal entities.

2. Reasons and Intent

(1) The rules that govern commerce in Redmont are spread across four Acts that amend each other in both directions. The same institution can be told to report monthly in one Act, quarterly in another, and to a schedule set by rule in a third.

(2) The financial regulation added by the Financial Institutions Enforcement Act works, but it sits outside the standards Act it was written to support, and its enforcement ladder cannot be found by the businesses it applies to.

(3) The list of financial institutions has been closed at four types since it was written. Payment services, custody, insurance and managed funds have no licence to apply for, so they either operate unregulated or do not operate at all.

(4) Reporting has grown faster than the economy that produces it. A one player company listed on an exchange currently owes the same monthly statements, prepared by a licensed accountant, as the largest bank in Redmont.

(5) This Act therefore restates commercial standards in one place, opens the list of financial institutions to a licence class ladder, replaces every separate reporting obligation with one tiered return, and states the Department's enforcement powers as a single ordered escalation.

3. Definitions

(1) For the purposes of this Act:

(a) Administrative Sanction. A coercive and non punitive measure imposed by the Department to compel compliance, including a penalty, a disgorgement order and a restitution order.

(b) Advertising Puffery. A vague or wildly exaggerated claim that no reasonable person would take seriously.

(c) Client Funds. Money or value a person receives and holds for or on behalf of a customer that is not a deposit, including funds held for custody, escrow, brokerage, settlement, investment under mandate or as a customer account balance.

(d) Commercial Advertisement. An advertisement intended to benefit or harm a privately owned or operated business.

(e) Deposit. An arrangement under which a person receives funds or value and is obligated, whether legally, contractually or in practice, to repay or return money or equivalent value, where one or more of the following applies:

(i) the principal is fixed, determinable or represented to be stable, and repayable at or near its original value on demand or within a determinable period;

(ii) the funds are withdrawable, redeemable or transferable on demand or on limited notice;

(iii) the holder is not exposed to a material risk of loss of principal under normal or reasonably foreseeable conditions;

(iv) the return is fixed, guaranteed, administratively determined or otherwise not materially dependent on the recipient's performance; or

(v) the arrangement is marketed or functions as a store of value, passive income, cash equivalent or means of payment.

(f) Department. The Department of Commerce.

(g) False Advertisement. A commercial advertisement containing untrue information that would deceive a reasonable person, where the advertiser acted knowingly. Where the information is publicly accessible, the advertiser is presumed to have been aware of it.

(h) Financial Institution. A person carrying on regulated financial activity, whether or not licensed and whether or not incorporated.

(i) Financial Product. Any instrument, token, account, contract or arrangement offered to the public that in substance constitutes a deposit, a security, an investment or another regulated financial interest, whatever it is called, and includes a depositary receipt issued under the Legal Entity Act.

(j) Fund. An arrangement pooling money or assets from more than one investor for collective investment, including an Exchange Traded Fund.

(k) Licence. An authorisation granted by the Department under Part V to carry on a class of regulated financial activity.

(l) Misleading Advertisement. A commercial advertisement containing true information presented in a way that may confuse or mislead a reasonable person, including by omitting information a reasonable person would consider in their decision making, by using ambiguous language, or by omitting the non serious or satirical intent of the advertisement.

(m) Operator. A person who carries on, controls, directs, manages, finances or materially participates in regulated financial activity, including an individual who receives, holds or disburses customer funds.

(n) Person. An individual or a legal entity, including a group of persons acting in concert.

(o) Political Advertisement. An advertisement intended to promote a political message, influence public opinion on a social issue, or persuade a person to support a candidate, party or policy.

(p) Public Company. A company whose securities are listed on a registered Stock Exchange in Redmont.

(q) Regulated Financial Activity. Carrying on, or holding oneself out as carrying on, the business of any of the following, whether or not it falls within a licence class under Part V: taking deposits; holding money or assets for another; lending or providing credit; dealing in, arranging deals in, or advising on financial products; managing money or assets for another; operating a trading venue, exchange or fund; underwriting or selling insurance; or providing payment, settlement or escrow services. Where an activity is within this definition but within no licence class, the Department shall allocate it to a class under section 17.

(r) Union. An organised association of workers formed to protect and advance their rights and interests.

(s) Whistleblower. A person with inside knowledge of an organisation who reports misconduct, dishonesty or illegal activity that may have occurred within it.

4. Interpretation

(1) For the purposes of this Act:

(a) the economic substance and practical effect of a transaction, instrument or arrangement prevails over its legal form, label or characterisation;

(b) a transaction includes a series of transactions or steps, whether or not documented, and rights or expectations may be express or implied and may arise from conduct, practice or marketing;

(c) designating a payment as a purchase, sale, donation, commodity, token or investment does not exempt it where it functions in substance as a deposit or another regulated financial product;

(d) carrying on regulated financial activity in contravention of this Act is a continuing course of conduct, and each day it continues is a fresh contravention; and

(e) where a provision admits more than one reading, the reading that best protects customers and prevents avoidance prevails.

(2) Any arrangement entered into wholly or mainly to avoid the application of this Act is disregarded, and this Act applies as if it had not been made. The use of a sham entity, nominee or intermediary to obscure the true Operator does not defeat liability or enforcement.

PART II — THE DEPARTMENT OF COMMERCE

5. Functions


(1) The Department is responsible for:

(a) the licensing and supervision of financial institutions;

(b) the integrity of markets and the protection of customers and depositors;

(c) the collection of the taxes imposed by Part IX;

(d) the investigation of commerce related white collar crime, findings being referred to the Department of Justice for prosecution; and

(e) the administration of the Company Register under the Legal Entity Act.

(2) Where it is unclear which department should investigate a crime, the matter is referred to the Department of Justice.

6. General Powers

(1) The Department may, subject to the notice and appeal procedure in section 54 and the escalation duty in section 44:

(a) monitor financial transactions and publish generalised reporting on transaction statistics;

(b) access the accounts of licensed financial institutions on request for the purpose of monitoring compliance;

(c) conduct random spot checks of gaming machines to verify advertised odds, non compliance being fraudulent trading;

(d) disband an in game company that does not meet the requirements to be a company, or that is used to carry on or disguise activity in contravention of this Act; and

(e) exercise the supervisory and enforcement powers in Part X.

(2) An employee of the Department engaged in the regulation of securities exchanges may not hold a security for less than 30 days.

7. Rulemaking

(1) The Department may make rules to give effect to this Act, including rules on licensing, fit and proper standards, client fund segregation, reporting forms, market conduct, and the operation of exchanges and funds.

(2) A rule must serve a legitimate governmental purpose and be reasonably tailored to achieve it, and must not conflict with this Act.

(3) A rule takes effect on publication.

(4) The Department may by rule impose a filing, a record keeping obligation or a periodic return on any person carrying on regulated financial activity, and on any Public Company or person operating a Fund. A rule doing so shall:

(a) state the burden it imposes and the purpose that burden serves;

(b) exempt a Tier 3 reporting person, unless the rule addresses the safety of customer funds; and

(c) not require information the person has already filed, or that is already available to the Department.

(5) A rule may not require a report from a person who is not carrying on regulated financial activity and is not a Public Company, a person operating a Fund or a tax exempt non-profit.

(6) Where the Department reasonably believes an emerging practice poses an immediate risk to customers or the financial system, it may issue an emergency temporary rule effective on publication, which lasts up to 60 days and may then be renewed or replaced only through ordinary rulemaking.

(7) Congress may disallow a rule by resolution of both chambers, and a rule so disallowed ceases to have effect and may not be remade in substantially the same terms in the same Congress.

8. Service Standards and Deemed Approval

(1) Where a person applies to the Department for a licence, a registration, a variation, an exemption, an advance ruling or the registration of a disclosure document, the Department shall decide the application within 14 days.

(2) The Department may, once per application, extend that period by a further 14 days by notice stating why.

(3) Where the Department does not decide within the applicable period, the application is deemed granted on the terms applied for, and the grant is provisional and revocable by the Department within a further 30 days.

(4) Deemed approval under subsection (3) is not available for:

(a) a licence in a class permitted to take deposits;

(b) an exemption, waiver or variation of any requirement of Part VI;

(c) a non objection to a qualifying holding under section 18(5); or

(d) the registration of a disclosure document under section 27.

(5) A refusal must state the reason and the steps required to cure it.

(6) This section does not apply where the applicant has failed to provide information the Department has requested, and the period is suspended until that information is provided.

9. Rights of Regulated Persons

(1) Information the Department requires from a person must satisfy a need to know principle. The Department does not always need the identity of account holders, and must have a reasonable justification for the data it requests, which it need not share.

(2) The Department may compel the production of information only in the course of its official duties.

(3) The Department and the Federal Reserve Bank shall treat the data of financial institutions as commercial in confidence, the sole exception being the use of strictly necessary data in a public report, and only to the extent required to describe and justify a regulatory or enforcement action.

(4) Data shared with the Department may also be shared with the Federal Reserve Bank, and with the Department of Justice or the Department of Homeland Security for the purposes of investigation, prosecution or financial stability.

PART III — WHISTLEBLOWERS

10. Whistleblowers


(1) Whistleblower protections are the protections provided to a whistleblower to enable them to come forward without fear of retribution or personal detriment.

(2) A person who in good faith reports a contravention of this Act is a whistleblower and is entitled to those protections and to the protections of the Criminal Code Act.

(3) No person may retaliate against a whistleblower.

(4) The Department may recommend to the Department of Justice the reduction or waiver of sanctions for an Operator or employee who voluntarily discloses a contravention and cooperates fully before being notified of an investigation.

PART IV — ADVERTISING AND FAIR TRADING

13. Advertising


(1) A person may not publish, or authorise the publication of, a false advertisement or a misleading advertisement.

(2) A person authorises an advertisement by displaying it of their own volition, or by agreeing to have another person display it on their behalf.

(3) The following are exempt from the definitions of false and misleading advertisement:

(a) advertising puffery; and

(b) political advertisements.

14. Financial Promotions

(1) A person may not make a false or misleading representation as to the safety, return, insurance or licensing status of a financial product.

(2) A person may not promote a deposit or financial product using representations of fixed, guaranteed, insured or risk free returns unless those representations are true and reasonably substantiated at the time they are made.

(3) A person may not represent, by name, advertising or conduct, that they are a bank, a licensed financial institution or an insured or government backed institution, unless they are licensed as such.

PART V — LICENSING OF FINANCIAL INSTITUTIONS

15. Requirement to be Licensed


(1) No person may carry on, or hold themselves out as carrying on, regulated financial activity unless that person is:

(a) an Incorporated Entity in good standing under the Legal Entity Act; and

(b) licensed by the Department for that activity.

(2) A person who receives deposits or client funds otherwise than through a licensed and incorporated financial institution contravenes this Act, notwithstanding any disclaimer, terms of service or characterisation of the funds as anything other than a deposit.

(3) Compliance with this Act does not relieve a person of any obligation under any other enactment.

(4) A licence states the classes the holder may carry on. A holder may apply at any time to add or surrender a class.

16. Licence Classes

(1) The licence classes are:

(a) Class A, Commercial Bank. May take deposits, lend and invest them for its own account, operate a reserve of less than 100%, and carry on any activity within Classes C to G.

(b) Class B, Credit Union. A member governed deposit taker formed as a cooperative or non-profit under the Legal Entity Act, whose leadership is democratically elected and whose surplus is distributed to members or reinvested for the benefit of all members. May carry on any activity within Classes C to E.

(c) Class C, Investment Firm. May broker securities, invest for clients under mandate, advise on investments, and lend. May not take deposits. May charge for its services.

(d) Class D, Custody and Payment Institution. May hold client funds and assets in custody, operate escrow and settlement, and process, route or store value for payment purposes. May not take deposits, lend client funds or invest them for its own account.

(e) Class E, Fund Manager. May establish, operate and manage a Fund, including an Exchange Traded Fund, and may market interests in it.

(f) Class F, Stock Exchange. The sole class able to list Redmont based securities for public trading. May charge commissions.

(g) Class G, Insurer. May underwrite and sell contracts of insurance, being contracts under which the insurer accepts a defined risk of a customer in exchange for a premium, and may hold and invest reserves against those contracts.

(h) Class H, Credit Provider. May lend to the public on its own account. May not take deposits or hold client funds. A Credit Provider shall make the disclosures required by the Credit Standards Act on every extension of credit, and shall not charge interest, fees or charges in excess of the limit in Section 20 of Part VII of the Criminal Code Act.

(2) A person may not carry on an activity reserved to a class it does not hold.

(3) An Investment Firm may not hold a taxation exemption on in game balances, but does not pay the Financial Institution Depositor Insurance Tax.

(4) The Department may attach to any licence conditions on permitted and prohibited activities, capital, reserves, client fund segregation, reporting and fit and proper standards, and may vary them on notice.

(5) An applicant for a licence shall hold, and a licensed institution shall maintain at all times, capital of not less than:

(a) $750,000 for a Class A Commercial Bank;

(b) $300,000 for a Class G Insurer;

(c) $250,000 for a Class F Stock Exchange;

(d) $150,000 for a Class D Custody and Payment Institution;

(e) $100,000 for a Class B Credit Union; and

(f) $75,000 for a Class C Investment Firm, a Class E Fund Manager or a Class H Credit Provider.

(6) Where an institution holds more than one class, the highest applicable figure applies.

(7) Capital for the purposes of subsection (5) must be equity within the meaning of section 36(4), must be paid up, and may not consist of client funds or deposits, of money borrowed from a connected person, or of a claim against a connected person. A connected person is an owner, Operator or related party within the meaning of section 38, or a person acting in concert with any of them.

(8) An institution shall hold the capital required by subsection (5) in unencumbered liquid assets. It may not lend, pledge, distribute or otherwise return that capital to an owner, Operator or connected person, and a transaction that has that effect is voidable at the instance of the Department. An applicant shall satisfy the Department as to the source of its capital, and shall not dispose of it for 90 days after the licence is granted.

(9) Capital counted towards the requirement for one institution may not be counted towards the requirement for another.

(10) The Department may by rule raise a figure in subsection (5), set an ongoing own funds requirement expressed as a proportion of an institution's assets or liabilities, and set a figure for a class of institution it designates under section 17. It may not lower a figure in subsection (5) for a class named in that subsection.

(11) An institution whose capital falls below the applicable requirement shall notify the Department within 48 hours and submit a plan to restore it. The Department may restrict the institution's activities, prohibit distributions, require the institution to stop taking new customers, or act under Part X until the requirement is met.

(12) The Department may by rule set fees for each licence class, as follows:

(a) an application fee, not exceeding 1% of the capital figure for that class in subsection (5);

(b) a supervisory fee, payable on the same cycle as the institution's reporting period under section 31, of not less than 1% and not more than 5% of that capital figure in aggregate over any 12 month period;

(c) the rate under paragraph (b) must be uniform for every institution holding the same licence class, and the Department shall publish the rate in force for each class;

(d) a fee must be proportionate to the supervisory burden the class imposes, and the Department may reduce or waive it for an institution in its first reporting period after licensing, or one that is winding down following the surrender or revocation of its licence;

(e) a supervisory fee is charged pro rata where an institution holds its licence for part of a period only, and is payable with the report due under Part VIII;

(f) a fee is a regulatory and compliance cost for the purposes of section 37(2)(d);

(g) fee revenue is directed to the DCGovernment account; and

(h) an unpaid fee is recoverable as a debt and is a ground for action under section 18(3).

(13) A Stock Exchange licence may not be held by, or by an affiliate of, an institution whose securities are listed on that exchange or that deals on it. An institution holding a Class F licence together with any other class shall keep the exchange function operationally separate, shall execute customer orders ahead of its own, and shall disclose any interest it has in a listed security. The Department may by rule set further conflict of interest and order handling requirements.

17. Designation of New Classes and Instruments

(1) The Department may by rule create, define, recognise and regulate a new licence class in addition to those in section 16, and may set the requirements that apply to it.

(2) This power is deliberately broad. The Department may bring within regulation any business dealing in deposits, investments, lending, custody, escrow, insurance, payments, funds or any other financial activity, however described, structured or labelled.

(3) The Department may by rule classify, define and regulate financial instruments, products and arrangements, including deposits, bonds, notes, securities, derivatives, foreign exchange, funds and tokens, and determine how any of them is treated under this Act.

(4) Where it is unclear whether an arrangement is a deposit, a security, an investment or another instrument, the Department may determine its classification by reference to its economic substance, and that determination governs unless set aside on appeal or by a court.

(5) A designated class or classified instrument carries the protections, obligations and enforcement consequences of this Act, and a person carrying on the activity without a licence contravenes this Act.

(6) A rule under this section may not create a new criminal offence, and may not apply retrospectively to conduct completed before its publication.

18. Fit and Proper Persons and Bar Orders

(1) The Department may assess whether a person seeking a licence, or acting as an Operator of a licensed institution, is fit and proper, having regard to honesty, prior contraventions and any Bar Order.

(2) A person subject to a Bar Order may not hold a licence, or operate, control or materially participate in any financial institution, for the duration of the Order.

(3) The Department may refuse, condition, suspend or revoke a licence where an Operator is not fit and proper or where continued operation would endanger customer funds.

(4) The Department may deregister a licensed institution for persistent non compliance, having considered investigatory and legal due diligence, the best interests of depositors, and restraint.

(5) A person shall notify the Department and obtain its non objection before acquiring, alone or acting in concert, a qualifying holding in a licensed financial institution, being an interest carrying 20% or more of its voting power, or an interest that makes that person its parent within the meaning of the Legal Entity Act.

(6) The Department shall decide within 14 days, and section 8 applies. It may object only where the acquirer is not fit and proper, where the acquisition would endanger the sound and prudent management of the institution or the safety of customer funds, or where the source of the funds for the acquisition has not been satisfactorily explained.

(7) Voting power acquired in contravention of subsection (5) is suspended until the Department gives its non objection, and the Department may direct the disposal of the holding.

(8) A licensed institution shall notify the Department within 7 days of becoming aware of a change in the identity of a person holding a qualifying holding in it.

19. Prohibited Conduct

(1) A person may not:

(a) take deposits, or offer interest, yield, payout or any return on a deposit, without a Class A or Class B licence;

(b) invest or manage funds for others, or offer a financial product to the public, without the appropriate licence; or

(c) contravene section 14.

(2) A person may not knowingly facilitate regulated financial activity carried on in contravention of this Act, including by hosting its infrastructure, processing or routing its payments, or advertising or promoting it. Accessory and accomplice liability under the Criminal Code Act applies.

(3) Nothing in this Act prohibits the issuance of bonds, notes or other debt instruments to raise capital for the issuer's own business, or dealing in securities, derivatives or foreign exchange, where conducted by or through an appropriately licensed institution or as the Department provides by rule. Such instruments are regulated as securities or investments and not as deposits, unless in substance they constitute deposit taking.

20. Advance Rulings

(1) A person may apply to the Department for a determination whether a proposed product, service or activity is regulated financial activity or requires a licence.

(2) The Department may issue a binding ruling, which it may make subject to conditions, and on which the applicant may rely while it remains in force.

(3) The Department may vary or revoke a ruling, with effect only from the date of variation or revocation, where the facts or the law have changed.

21. Regulatory Sandbox

(1) The Department may permit a person to test a new or innovative financial product, service or model under supervision, on conditions and for a limited period it sets, with such modifications to the requirements of this Act as it considers appropriate.

(2) Participation does not exempt the person from liability to customers, and the Department may end participation at any time.

(3) The Department may set the eligibility, safeguards and customer protections that apply.

PART VI — CLIENT MONEY, DEPOSITS AND GUARANTEE

22. Client Funds


(1) A licensed institution other than a Commercial Bank or Credit Union that receives client funds shall:

(a) hold them as liquid cash or on deposit with a Commercial Bank or Credit Union;

(b) keep them fully segregated from its own funds; and

(c) not lend, pledge, invest or otherwise use them for its own account or to meet its own liabilities or operating costs.

(2) Client funds may be invested only as agent under the customer's mandate, with the customer bearing the investment risk, and only by an institution licensed for that activity.

(3) Client funds are the property of the customer, do not form part of the institution's estate, and are not available to its creditors.

(4) An institution holding client funds shall identify each customer's entitlement in its records, and shall not hold with any one Commercial Bank or Credit Union an amount of client funds exceeding what the deposit guarantee would cover for the customers concerned. Where a bank holding client funds fails, the shortfall is borne by the customers pro rata, and the holding institution is liable for any part of the shortfall attributable to its breach of this subsection.

(5) The Department may by rule set the manner of segregation, reconciliation and reporting of client funds, may determine what constitutes client funds and permitted use, and may grant an exemption from any requirement of this section other than subsections (1)(b), (1)(c) and (3).

23. Deposits

(1) Only a Commercial Bank or a Credit Union may take deposits, and only a Commercial Bank may lend or invest deposits for its own account and operate a reserve of less than 100%.

(2) A Credit Union shall operate the reserve its licence conditions require.

(3) The Federal Reserve Bank sets and enforces reserve ratios and monetary reserve requirements for deposit taking institutions. Where this Act empowers the Department to set a reserve requirement, the Department shall act in consultation with the Federal Reserve Bank and consistently with the requirements it sets. This does not affect the Department's authority over client fund segregation, licensing, conduct or enforcement.

(4) A Commercial Bank is owned by an owner or group of owners who may make all decisions regarding the bank, its investments, employees and rates. Its profits are shared among its owners as its constitution provides.

24. Deposit Guarantee

(1) The Federal Government guarantees deposits of up to $100,000 per person, per licensed deposit taking institution.

(2) For the purposes of subsection (1):

(a) a person and their alternate accounts are one person;

(b) all accounts a person holds at the same institution are aggregated; and

(c) the covered amount is reduced by any amount that person owes the institution and that is due or capable of set off.

(3) The guarantee does not cover:

(a) a deposit held by, or for the benefit of, an owner, Operator, related party or connected person of the institution, or a person acting in concert with any of them;

(b) a deposit made by a person who caused or materially contributed to the failure of the institution;

(c) a deposit of funds known to the depositor to be derived from criminal activity; or

(d) a deposit taken by a person who was not licensed to take it.

(4) Where a licensed institution holds client funds on behalf of identified customers in accordance with section 22, the guarantee applies to each of those customers separately and not to the holding institution as a single depositor.

(5) Every licensed deposit taking institution is automatically covered. Coverage continues for 30 days after deregistration, surrender of the licence, or the institution ceasing to take deposits, whichever occurs first.

(6) The guarantee is Financial Institution Depositor Insurance and is compulsory for the stability of the financial system. It is funded by the Financial Institution Depositor Insurance Tax imposed by section 34(2) and by any contribution the Department sets by rule under subsection (7). Contributions offset past and future payouts but do not imply an exhaustive fund.

(7) The Department may by rule require a licensed deposit taking institution to pay a contribution calculated by reference to the covered deposits it holds and the risk it presents, and may set a lower contribution for an institution that holds capital above the requirement in section 16(5).

(8) A licensed deposit taking institution may not hold covered deposits exceeding ten times the capital it is required to hold under section 16(5) unless the Department approves the excess and imposes additional capital or conditions to match it. An institution that exceeds the limit shall notify the Department within 48 hours, and the Department may restrict its taking of further deposits or act under Part X.

(9) Where an institution fails, the Department shall determine each covered depositor's entitlement and pay it within 14 days of the failure, or within 14 days of the depositor establishing their entitlement, whichever is later. A depositor who does not claim within 3 months of the failure ceases to be entitled under the guarantee, but keeps their claim against the estate.

(10) On paying a depositor under this section, the Government is subrogated to that depositor's claim against the institution to the extent of the payment, and ranks as a Class 2 claim under Part VI of the Bankruptcy Act. A depositor may not recover the same loss twice.

(11) The Department may recover the cost of a payout from the institution, and may sell a collapsed institution or part of one to another party where that is in the best interests of depositors.

(12) The Department may recover the cost of a payout from a director, manager or Operator of the failed institution only where that person is liable under section 53 of this Act, section 11(6) or section 73 of the Legal Entity Act, or by order of the Federal Court. A recovery under this subsection shall be effected with the least practicable disruption to the estate targeted.

(13) Once subsections (11) and (12) are exhausted, the Department is pre authorised to use unappropriated Government funds to satisfy the guarantee. Where the amount required exceeds ten times the capital the institution was required to hold under section 16(5), the excess requires an appropriation by Congress.

(14) The Department may apply to the Federal Court to dismiss or stay a bankruptcy petition by or against a licensed financial institution, and may instead proceed under section 25 or section 50 of this Act. Where a petition has been accepted, the Department may apply within 14 days to set it aside on the ground that it was obtained by concealment or misrepresentation. A decision or application under this subsection is subject to section 54 and does not affect a right acquired in good faith in reliance on the earlier position.

(15) Where the Department disbands an in game company under section 6(1)(d), all customer funds and client funds held through it shall first vest in a receiver appointed under section 50, and the disbandment takes effect only once that receiver has been appointed.

(16) A licensed deposit taking institution shall state, wherever it advertises or offers a deposit, that deposits are guaranteed up to $100,000 per person and that the guarantee is subject to this section.
25. Commandeering

(1) In extraordinary circumstances, including insolvency, near insolvency, financial crisis, or where continued operation poses a systemic risk to the financial system or to depositors, the Department may take temporary control of a financial institution.

(2) Control under this section lasts no longer than 72 hours unless extended by the Federal Court on an application for receivership under section 50.

PART VII — MARKETS, SECURITIES AND FUNDS

26. Stock Exchanges


(1) The Department may monitor the operations of a Stock Exchange with full access to its trading channels and data.

(2) A Stock Exchange may not calculate the market price of shares in a Public Company using any factor other than the market supply of and demand for those shares, and is responsible for updating those prices without further input from the company.

(3) Each listed company must have its price updated at least once every 30 days.

(4) The Department may make rules for the operation of Stock Exchanges for the purpose of preserving their stability and preventing or investigating illicit activity.

27. Offering Disclosure

(1) A person may not offer a security or financial product to the public unless a disclosure document in the form the Department requires has been filed with and registered by the Department.

(2) The disclosure document shall fairly present the nature of the offering, the risks, the use of funds and the financial position of the issuer.

(3) The Department may refuse, suspend or revoke the registration of a disclosure document that is inadequate, inaccurate or misleading.

(4) The following are exempt from subsection (1):

(a) an offering made only to persons who have held an interest in the issuer, acquired for value, for at least 90 days;

(b) an offering made to fewer than 10 persons, counted together with every other offering by the issuer and its affiliates in the preceding 12 months;

(c) an offering with a total value of less than 500 penalty units, counted together with every other offering by the issuer and its affiliates in the preceding 12 months; and

(d) any offering or class of offering the Department exempts by rule or order.

(5) An exemption from subsection (1) is not an exemption from section 14.

28. Funds

(1) A Fund may be operated only by a Class E Fund Manager.

(2) An Exchange Traded Fund is a Fund whose interests are listed for trading on a Stock Exchange.

(3) A Fund Manager shall hold the assets of a Fund separately from its own and from those of any other Fund it manages, and section 22 applies to those assets.

(4) The Department may by rule set the valuation, redemption and disclosure requirements of Funds.

29. Trading Suspension and Product Intervention

(1) The Department may by order suspend or halt trading in a security, financial product or listing where it reasonably believes the available information is inadequate or inaccurate, the market is disorderly, or suspension is necessary to protect customers or investors.

(2) The Department may by order prohibit, suspend or restrict the offering of a financial product or arrangement that it reasonably believes poses a risk of harm to customers or the financial system. The order may apply to a named product or person or to a class.

(3) An order under this section takes effect on publication and remains in force for the period stated, which the Department may extend or lift.

PART VIII — REPORTING AND AUDIT

30. Single Reporting Regime


(1) This Part states the whole of the periodic reporting owed to the Department, to a Stock Exchange and to the public by a licensed financial institution, a Public Company and a person operating a Fund.

(2) No other periodic report may be required of such a person by rule, by an exchange, or by a licence condition, except a report the Department requires from a single named institution for a stated supervisory reason and for a stated period.

(3) A single report satisfying the requirements of this Part satisfies every obligation to report the same information, however arising.

31. Reporting Tiers

(1) A reporting person falls into a tier by the greater of its own total assets and the total client funds and Fund assets it holds or administers, averaged over the reporting period:

(a) Tier 1, total assets of $1,000,000 or more, or holding a Class A or Class F licence: reports monthly;

(b) Tier 2, total assets of $100,000 or more but less than $1,000,000: reports monthly;

(c) Tier 3, total assets of less than $100,000: reports quarterly.

(2) A tax return under Part IX is filed on the same cycle as the reporting person's tier, and a taxation period for a Tier 2 or Tier 3 institution is its reporting period.

(3) The Department may move a person to a higher tier by notice stating a supervisory reason, and may move a person to a lower tier on request where it has met the threshold for a full reporting period.

(4) A person that has moved between tiers reports on its new cycle from the start of the next reporting period.

32. Contents of a Report

(1) A report shall contain:

(a) a balance sheet;

(b) an income statement;

(c) a statement of changes in equity, for a Tier 1 reporting person only;

(d) a cash flow statement, for a Tier 1 reporting person only; and

(e) a management discussion and analysis addressing, so far as applicable:

(i) significant changes in financial condition, operations or performance since the last report;

(ii) a summary of investment activity, capital resources and major assets, liabilities and financing arrangements, and for a Fund, its strategy, allocation, major holdings, performance, distributions and change in total value;

(iii) any regulatory action, legal proceeding, contractual dispute or other material event that may affect the person's position or operations; and

(iv) the person's compliance status with applicable requirements.

(2) A Tier 3 reporting person may satisfy subsection (1)(e) with a short narrative and is not required to address a matter that does not apply to it.

(3) A report shall be prepared in accordance with generally accepted accounting standards or, at the person's election, International Financial Reporting Standards.

(4) A report is due within 30 days of the end of the reporting period.

(5) The report of a Public Company or a Fund shall be made publicly available in a downloadable form through the Stock Exchange on which it is listed and, where applicable, its Discord.

33. Accountants and Audit

(1) The report of a Tier 1 or Tier 2 reporting person shall be prepared and submitted by a licensed accountant with their name attached.

(2) The report of Tier 3 reporting person may be prepared by any person, and shall be signed by a director or manager who certifies that it is true to the best of their knowledge.

(3) A Public Company shall disclose its audit status alongside its report, being:

(a) Audited, where it has received a statutory audit in the previous 6 months, stating the date of that audit and who conducted it; or

(b) Unaudited, where it has not.

(4) A statutory audit shall give a fair and impartial assessment of the financial health of the person audited, validate its reported statements, and confirm compliance with financial law. It must verify the existence and fair valuation of each item on the balance sheet, and the existence and legitimacy of the cash flows on each line of the income statement.

(5) An assessment that does not meet subsection (4) may not be labelled an audit by a Public Company or a Stock Exchange.

(6) Records supporting a report shall be retained for not less than 12 months, and indefinitely where they relate to a matter under investigation.

PART IX — TAXATION OF FINANCIAL INSTITUTIONS

34. Tax Imposed


(1) A Financial Institution Tax of 15% is imposed on the taxable income of every licensed financial institution for each taxation period.

(2) A Financial Institution Depositor Insurance Tax of 10% is imposed on the taxable income of every licensed deposit taking financial institution for each taxation period.

(3) Both taxes apply to the same taxable income.

(4) Licensed deposit taking financial institutions are exempt from all balance taxes under the Taxation Act from the point of licensing. The Department may withdraw the exemption where the institution does not meet the requirements of this Act.

(5) A licensed deposit taking financial institution that holds a balance tax exemption pays instead a deposit tax of 1% monthly.

(a) The tax is charged on the average balance held in the accounts of the institution over the taxation period, measured by daily sampling or by such other method as the Department sets by rule.

(b) The following are excluded from the base of the deposit tax:

(i) capital the institution is required to hold under section 16(5);

(ii) any reserve the Federal Reserve Bank requires it to hold; and

(iii) client funds held for identified customers under section 22.

(c) Lending, investing, paying out, or otherwise deploying deposits in the ordinary course of the institution's business is not avoidance of the deposit tax.

(d) A transfer made wholly or mainly to reduce the deposit tax, including a transfer to a related party or to another account that is reversed after the end of the taxation period, is disregarded, and the amount transferred is included in the base.

(e) The deposit tax is administered by plugin, or by the Department if no plugin is implemented, and the Department may make rules necessary to enforce it.

(f) The deposit tax does not apply to an institution while it is in receivership under section 50, while a bankruptcy case under the Bankruptcy Act is on foot in respect of it, or while it is winding down following the surrender or revocation of its licence. Relief under this paragraph ends when that process ends.

35. Taxation Period

(1) A taxation period is a calendar month for a Tier 1 institution, and otherwise the institution's reporting period under section 31.

(2) Taxable income is determined separately for each taxation period.

36. Computation of Income

(1) Accounting income for a taxation period is the net increase in the institution's equity arising from all increases in assets and all decreases in liabilities, other than contributions of capital by an owner, and is increased by the amount of every dividend, distribution, buyback, redemption, deemed dividend and other transfer of value to an owner or related party made during the period.

(2) Taxable income is accounting income as adjusted by this Part.

(3) An unrealised gain, and any other amount that is not realised, is excluded from taxable income.

(4) For the purposes of this Part, an interest in an institution is equity only if it:

(a) exposes the holder to a genuine and unrestricted risk of loss of principal;

(b) provides returns that are variable and materially dependent on the institution's performance;

(c) is not redeemable, retractable, repurchaseable or callable at a fixed, guaranteed or predetermined amount other than on dissolution or bankruptcy;

(d) gives no contractual, implied or practical entitlement to liquidity, withdrawal or repayment on demand or within a determinable period;

(e) is fully subordinated in all circumstances to the claims of depositors and other creditors; and

(f) contains no feature, side agreement or understanding whose purpose or effect is to preserve capital, act as a store of value or otherwise replicate a deposit.

37. Deductions

(1) An institution may deduct only expenses that are incurred for the purpose of earning income and are reasonable in the circumstances and in amount.

(2) Without limiting subsection (1), the following are deductible:

(a) interest expenses;

(b) ordinary operating and administrative expenses;

(c) employee compensation up to $25,000 per employee, and only where the employee performed genuine services of at least that value;

(d) regulatory and compliance costs; and

(e) credit losses, to the extent realised in the taxation period.

(3) No deduction may be made for:

(a) a dividend or other distribution to an owner;

(b) a share buyback, redemption or other equity repurchase;

(c) so much of an amount paid or payable to a related party as exceeds fair market value for the goods, services or use of money actually provided, fair market value being the price that would be agreed between parties dealing at arm's length;

(d) an expense providing a direct or indirect benefit to an owner or related party, including housing, vehicles, luxury goods or services, memberships, subscriptions, private services, or entertainment not strictly required for business operations;

(e) employee compensation above $25,000 per employee;

(f) the acquisition or improvement of a capital asset, being property acquired or held for continuing use in the business and not held primarily for resale, except that the institution may deduct one twelfth of the cost of the asset in each of the twelve months following its acquisition; or

(g) an expense lacking economic substance or incurred primarily to reduce taxable income.

38. Related Parties and Deemed Dividends

(1) A related party is:

(a) an owner holding 10% or more of the equity of the institution, or exercising control over it;

(b) an entity controlled by, or at least 50% owned by, such a person; and

(c) an entity controlled by, or at least 50% owned by, the institution itself.

(2) Control is the ability, whether direct or indirect and whether exercised or not, to determine, influence or direct the strategic, financial or operational decisions of an entity, whether through voting interests or contractual rights. A person is not a related party by reason only of being a customer, depositor or lender of the institution on ordinary commercial terms.

(3) An amount paid or payable as salary, wages, bonus or other compensation to a person described in subsection (1)(a) is deemed to be a dividend and is not deductible.

39. Losses

(1) A loss may be carried forward and offset against income in the following three months.

(2) A loss not applied within that period expires.

40. Filing and Payment

(1) An institution shall file a tax return with the Department for each taxation period, in the form the Department prescribes, within 30 days of the end of the period. The return is filed together with the report required by Part VIII and forms part of it.

(2) Tax is payable within 30 days of the end of the taxation period.

(3) Where a return has not been filed by the time tax becomes payable, the amount due is the tax payable for the preceding taxation period, or the institution's reasonable estimate for the current period.

(4) Interest accrues daily at 1% per day on tax that remains unpaid after the due date, and is payable and enforceable as tax.

(5) Interest on a deficiency runs from the original due date, whether or not a return was filed and whether or not the amount paid was based on a reasonable estimate.

(6) Where the amount paid exceeds the tax payable, the Department shall refund the excess within 30 days of receiving the return.

(7) An institution that fails to file a return is liable to a penalty of $1,000 per day from the filing deadline, rising to $2,500 per day on a repeated failure. The penalty may not exceed the greater of $25,000 and the tax payable for the period to which the return relates.

41. Records, Assessment and Appeal

(1) An institution shall maintain records sufficient to establish its accounting income, its taxable income, the nature and amount of each deduction claimed, and its compliance with this Part.

(2) The burden of establishing the correctness of a return and the entitlement to a deduction rests on the institution. Where an institution fails to provide sufficient evidence of an amount, the Department may disregard it and determine the tax consequences accordingly.

(3) The Department may inspect, examine or audit the books, records and affairs of an institution, and may require it to produce documents, provide explanations and reconciliations, identify the parties to a transaction, demonstrate the commercial purpose of a transaction, and establish the source and nature of any payment, receipt, asset or liability. Failure to comply permits the Department to draw adverse inferences.

(4) Where the Department is not satisfied with the accuracy or completeness of a return, it may determine the income and tax payable, and in doing so may deny an unestablished deduction, include an unreported amount, recharacterise a transaction according to its economic substance, substitute fair market value for a non arm's length transaction, and disregard an artificial or avoidance arrangement. A determination may be based on available records, reasonable assumptions and estimates.

(5) The Department may assess or reassess tax, interest and penalties, and shall issue a notice stating the period, the amounts and the basis of the assessment in reasonable detail. An assessment is presumed correct unless the institution establishes otherwise.

(6) The Department may reassess a return within 12 months of its filing, and at any time where the return was knowingly filed incorrectly.

(7) An institution may appeal an assessment by filing a notice of appeal with the Department within 7 days of the notice of assessment, specifying the grounds and including the material relied on. An appeal may be brought only on the ground that the assessment contains a factual error, misapplies this Act, or is unreasonable on the available evidence.

(8) An appeal is reviewed by the Secretary of the Department, or by a designated officer not involved in the original assessment where practicable, who may confirm, vary or vacate the assessment. One further administrative appeal lies against a reassessment, after which the decision is final for the purposes of this Act.

(9) An institution dissatisfied with a final decision may seek relief before the Federal Court. Tax remains payable and continues to accrue interest during any appeal unless the Court orders otherwise.

42. Voluntary Disclosure

(1) An institution, or a director, officer or employee of one, may make a voluntary disclosure to the Department of any understatement of income, overstatement of deductions, failure to report, or other non compliance with this Part.

(2) A disclosure is valid only where it is made voluntarily and before the person is notified of an audit or investigation into the subject matter, receives an assessment relating to it, or becomes aware that enforcement action is intended, and where it is complete and accurate and the person cooperates fully in correcting the deficiency.

(3) Where a disclosure is valid:

(a) no prosecution may be commenced under the Criminal Code Act in respect of the disclosed conduct;

(b) any penalty may be reduced or waived at the Department's discretion; and

(c) the institution shall be given a reasonable period to file amended returns, provide records and pay the tax owing.

(4) Relief does not apply where the disclosed conduct involved deliberate fraud, falsification of records or intentional deception, or where the disclosure is incomplete or misleading, but the Department may grant partial relief where the disclosure substantially assists in resolving non compliance and it is in the public interest to do so.

PART X — SUPERVISION AND ENFORCEMENT

43. Investigation


(1) The Department may supervise, investigate and enforce compliance with this Act in respect of any person reasonably suspected of carrying on regulated financial activity, whether or not licensed or incorporated, and may exercise its powers against an Operator personally.

(2) The Department may by notice require such a person or Operator to produce records, transaction logs, communications and account data, to identify all persons, accounts, customers and amounts involved, and to account for the location and disposition of all customer funds.

(3) On the opening of an investigation or the service of a notice, the person and every Operator shall preserve all relevant records and data and shall not delete, alter, conceal or destroy them.

(4) Failure to comply permits the Department to draw adverse inferences and to proceed on any reasonable basis.

(5) The Department may conduct test transactions, including by posing as a customer, to verify compliance, and information so obtained may be used in any investigation, sanction or proceeding.

44. Escalation

(1) The powers in sections 45 to 50 are an escalation. The Department shall use the least intrusive power adequate to the risk, and shall record in the notice why a more intrusive power was necessary where it uses one.

(2) Nothing in subsection (1) prevents the Department acting immediately where customer funds are at risk of dissipation, concealment or loss.

45. Independent Audit and Monitors

(1) The Department may require a licensed institution, or a person reasonably suspected of carrying on regulated financial activity, to obtain and submit an independent audit of its accounts, funds and customer liabilities, prepared by a licensed accountant and at the expense of the person audited.

(2) The Department may appoint an independent monitor to a licensed institution to observe, report on and supervise its compliance, where its concerns fall short of requiring receivership. The institution shall give the monitor full access to its records, accounts and personnel and shall bear the monitor's reasonable costs.

(3) Failure to comply with, or obstruction of, an audit or a monitor permits the Department to draw adverse inferences and to proceed on any reasonable basis.

46. Enforceable Undertakings

(1) The Department may accept a written undertaking from a person to do, or refrain from, any act in order to remedy or prevent a contravention, including to cease activity, segregate or return funds, or compensate customers.

(2) An accepted undertaking is binding, and the Department may apply to the Federal Court to enforce it.

47. Cease and Desist Orders

(1) Where the Department reasonably believes a person is carrying on regulated financial activity in contravention of this Act, it may issue a binding Cease and Desist Order requiring that person to stop the activity, the related advertising and the acceptance of further funds immediately, and may require the person to honour outstanding withdrawal or repayment requests.

(2) The Order takes effect on service and remains in force unless stayed or set aside.

48. Freeze Orders and Third Party Directions

(1) Where the Department reasonably believes customer funds are at risk of dissipation, concealment or loss, it may issue a Freeze Order restraining the transfer or disposal of specified funds or assets held by or on behalf of an Operator, including funds in an Operator's personal balance.

(2) A Freeze Order may be issued without prior notice, takes effect immediately on service, and shall be limited to the amount reasonably necessary to protect customer funds and satisfy potential restitution.

(3) A Freeze Order lapses 72 hours after service unless within that period the Department applies to the Federal Court to extend or confirm it. The Court may extend, vary, confirm or discharge it and make any further order necessary to preserve customer funds.

(4) The Department may direct any third party holding funds, assets, records or infrastructure of or for an Operator, including an exchange, payment provider, custodian or host, to freeze, preserve, produce or deliver them. A third party that complies in good faith is immune from liability for doing so.

49. Asset Tracing and Recovery

(1) The Department may trace customer funds through any account, balance or transaction, including funds moved to an Operator's personal balance or to a third party.

(2) The Department may seize the assets of an Operator, with the least practicable disruption to their estate, and apply them to the restitution of customers and the costs of enforcement.

(3) Where a third party received customer funds otherwise than in good faith and for fair value, the Department may recover those funds from that third party for the benefit of customers.

(4) This section operates alongside the Proceeds of Crime provisions of the Criminal Code Act and the Knowing Receipt provisions of the Redmont Civil Code Act.

50. Receivership

(1) Where the Department reasonably believes it necessary to protect customer funds, it may apply to the Federal Court to place an operation carrying on regulated financial activity, together with the relevant assets of its Operators, into receivership, whether or not the operation is licensed or incorporated.

(2) A receiver so appointed has, in addition to the powers of a receiver under the Legal Entity Act, the power to take control of all customer funds and operational assets, suspend the activity and wind down the operation.

(3) The receiver shall apply recovered assets first to the restitution of customers, and thereafter to creditors, penalties and the costs of the receivership.

(4) Pending a receivership application the Department may act under section 25.

51. Sanctions, Disgorgement and Restitution

(1) Administrative sanctions under this Act are coercive and not punitive.

(2) Where the Department determines that a person has contravened this Act, it may impose a proportionate administrative penalty, order the disgorgement of any profit or benefit derived from the contravention, and order restitution to affected customers.

(3) Amounts recovered, including frozen, seized and disgorged funds, are applied first to the restitution of customers and thereafter to penalties and enforcement costs.

(4) An administrative sanction may be contested before a judicial officer in accordance with the Redmont Civil Code Act, and does not bar criminal prosecution for the same conduct.

52. Public Warnings, Bar Orders and the Public Register

(1) The Department may issue public warnings identifying an unlicensed person or operation and stating that it is unlicensed and uninsured.

(2) The Department may by Bar Order prohibit a named individual from operating, controlling or materially participating in any financial institution for a specified period, where that individual has operated an unlicensed scheme or seriously or repeatedly contravened this Act.

(3) The Department shall maintain a public register of licences, Cease and Desist Orders, Freeze Orders, Bar Orders, product intervention orders and trading suspensions.

53. Personal Liability of Operators

(1) Every Operator of an operation that carries on regulated financial activity in contravention of this Act is personally, jointly and severally liable for the repayment of customer deposits and for any penalty, disgorgement or restitution ordered.

(2) Where the activity is carried on without a licensed and incorporated entity, no limitation of liability applies and the Operators are liable as principals.

(3) Liability is not avoided by characterising the funds as a purchase, investment, commodity or token, by the resignation, removal or substitution of an Operator after the conduct, by the transfer or purported transfer of ownership or control, or by reliance on terms to which customers did not demonstrably and knowingly assent.

54. Notice, Appeals and Court Recourse

(1) On issuing an order or sanction, the Department shall serve notice stating the order, the conduct concerned and the basis for it in reasonable detail. Service in respect of an unincorporated operation may be effected on any Operator.

(2) A person subject to an order or sanction may appeal to the Secretary of the Department, or to a designated officer not involved in the original decision, within 7 days of service. The reviewing authority may confirm, vary or set aside the order.

(3) A person dissatisfied with the decision on appeal may seek relief before the Federal Court.

(4) An order or sanction remains in force during an appeal unless stayed by the Secretary or the Federal Court, and nothing in this section limits the Court's power to grant urgent relief or to preserve customer funds.

(5) The Department acts on reasonable belief. Where a sanction is contested before a judicial officer, the standard of proof is that set by the Redmont Civil Code Act for administrative violations.

55. Delegation and Immunity

(1) The Secretary may delegate any power under this Act to an officer or delegate of the Department, except the power to make rules.

(2) The Department, its officers and any receiver or monitor appointed under this Act are immune from civil liability for acts done in good faith in the exercise of their powers. The immunity does not apply to criminal conduct or to acts outside the scope of their authority.

PART XI — OFFENCES AND CIVIL VIOLATIONS

56. Amendments to the Criminal Code Act


(1) Part VII of the Criminal Code Act is amended by adding the following sections, numbered sequentially after the last existing section of that Part:
Operating an Unlicensed Financial Institution
Offence Type: Indictable
Penalty: Up to 1000 Penalty Units; Up to 60 minutes imprisonment.

A person commits an offence if the person carries on, operates, or knowingly facilitates regulated financial activity, including taking deposits or offering interest, yield or a payout on funds received, without the licence and incorporation required by the Commercial Standards Act.
​
Aggravated Operation of an Unlicensed Financial Institution
Offence Type: Indictable
Penalty: Up to 1500 Penalty Units; Up to 60 minutes imprisonment; Restitution.

A person commits an offence if the person commits the offence of Operating an Unlicensed Financial Institution and one or more of the following applies:

(a) the total customer funds taken or placed at risk exceed 500 Penalty Units in value;

(b) the scheme targeted new players or otherwise exploited the inexperience of customers;

(c) customer funds were dissipated, concealed or moved to a personal balance; or

(d) the person had previously been warned, sanctioned or barred in respect of similar conduct.
​
Operating a Ponzi or Pyramid Scheme
Offence Type: Indictable
Penalty: Up to 2000 Penalty Units; Up to 60 minutes imprisonment; Restitution; Disgorgement of any benefit derived.

A person commits an offence if the person:

(a) operates, promotes or induces participation in an arrangement; and

(b) returns, payouts or yields to existing participants are paid wholly or substantially from contributions made by new participants rather than from genuine revenue or investment profit.
This offence shall not occur where:

(c) the returns are genuinely and substantially derived from the lawful trading or investment activity of a licensed financial institution.
​
Misuse of Client Funds
Offence Type: Indictable
Penalty: Up to 1000 Penalty Units; Up to 60 minutes imprisonment; Restitution of the funds or their value.

A person commits an offence if the person:

(a) receives or holds client funds as defined in the Commercial Standards Act; and

(b) lends, pledges, invests, encumbers or otherwise applies them for the person's own account or to meet the person's own liabilities or operating costs, or fails to keep them segregated as required by that Act.
It is a defence if the person:

(c) applied the funds strictly as agent under the customer's mandate, with the customer bearing the investment risk.
​
Breach of a Cease and Desist Order
Offence Type: Indictable
Penalty: Up to 750 Penalty Units; Up to 45 minutes imprisonment.

A person commits an offence if the person continues, resumes or causes the continuation of an activity after being served a Cease and Desist Order under the Commercial Standards Act. Each day of continued contravention is a separate offence.
​
Dissipation of Frozen Funds
Offence Type: Indictable
Penalty: Up to 1000 Penalty Units; Up to 60 minutes imprisonment.

A person commits an offence if the person transfers, withdraws, conceals or disposes of funds or assets in contravention of a Freeze Order issued under the Commercial Standards Act.
​
Breach of a Product Intervention or Trading Suspension Order
Offence Type: Indictable
Penalty: Up to 750 Penalty Units; Up to 45 minutes imprisonment. Each day of continued contravention is a separate offence.

A person commits an offence if the person offers, deals in or trades a financial product or security in contravention of a product intervention order or a trading suspension order issued under the Commercial Standards Act.
​
Obstruction of Financial Regulation
Offence Type: Indictable
Penalty: Up to 500 Penalty Units; Up to 30 minutes imprisonment.

A person commits an offence if the person obstructs, hinders or misleads the Department of Commerce in the exercise of its powers under the Commercial Standards Act, fails to comply with a lawful order, direction, requirement, undertaking or audit demand under that Act, or deletes, alters, conceals or destroys records the person is required to preserve.
​
Tipping Off
Offence Type: Indictable
Penalty: Up to 300 Penalty Units; Up to 30 minutes imprisonment.

A person commits an offence if the person:

(a) knows or suspects that an investigation under the Commercial Standards Act is being, or is likely to be, conducted; and

(b) discloses information to the subject of the investigation, or to any other person, in a manner likely to prejudice the investigation.
​
False Representation as a Financial Institution
Offence Type: Indictable
Penalty: Up to 400 Penalty Units; Up to 30 minutes imprisonment.

A person commits an offence if the person:

(a) represents, whether by name, advertising, conduct or otherwise, that the person is a bank, a licensed financial institution or an insured or government backed institution; and

(b) the person is not licensed as such under the Commercial Standards Act.
​
Unlawful Offering of a Security or Financial Product
Offence Type: Indictable
Penalty: Up to 500 Penalty Units; Up to 30 minutes imprisonment.

A person commits an offence if the person:

(a) offers a security or financial product to the public without a disclosure document registered by the Department of Commerce; or

(b) offers a security or financial product on the basis of a disclosure document the person knows, or ought reasonably to know, is materially false or misleading.
This offence shall not occur where:

(c) the offering, or a class of offerings to which it belongs, is exempt from the disclosure requirement under the Commercial Standards Act.
​
Reckless Facilitation of Unlicensed Financial Activity
Offence Type: Indictable
Penalty: Up to 500 Penalty Units; Up to 30 minutes imprisonment.

A person commits an offence if the person:

(a) hosts the infrastructure of, processes or routes payments for, or advertises or promotes, regulated financial activity carried on in contravention of the Commercial Standards Act; and

(b) is reckless as to whether that activity is unlicensed.
It is a defence if the person:

(c) took reasonable steps to verify the licensing status of the activity before providing the facilitation.
​
Operating or Participating While Barred or Disqualified
Offence Type: Indictable
Penalty: Up to 1000 Penalty Units; Up to 60 minutes imprisonment; Extension of the Bar Order or disqualification by up to 2 months.

A person commits an offence if the person:

(a) is subject to a Bar Order under the Commercial Standards Act or to a disqualification order under the Legal Entity Act; and

(b) operates, controls, manages, finances or materially participates in a financial institution or legal entity in a capacity prohibited by that Order, whether directly or through a nominee, intermediary or other person.
This offence shall not occur where:

(c) the person acted with the prior written authorisation of the Department of Commerce.
​
Wash Trading and Matched Orders
Offence Type: Indictable
Penalty: Up to 500 Penalty Units; Up to 30 minutes imprisonment; Disgorgement of any benefit derived.

A person commits an offence if the person:

(a) enters into a transaction in a security or financial product that involves no change in beneficial ownership; or

(b) enters an order to buy, or to sell, knowing that a matching order of substantially the same size and price has been or will be entered by the same person or by a person acting in concert with them; and

(c) does so for the purpose of creating a false or misleading appearance of trading activity or price.
​
Front Running
Offence Type: Indictable
Penalty: Up to 500 Penalty Units; Up to 30 minutes imprisonment; Disgorgement of any benefit derived.

A person commits an offence if the person:

(a) knows that a customer, employer or client has placed, or intends to place, an order in a security or financial product that is likely to affect its price; and

(b) deals in that security or product, or causes another to do so, ahead of that order for the benefit of themselves or a person other than the customer.
​

(2) Section 17 (Persistent Corporate Violation), in Part X of the Criminal Code Act, is amended as follows:
(c) has received more than three warnings from the DOC within 2 weeks.​
(c) has received more than three warnings from the DOC concerning the same or related conduct, or has persistently violated the Legal Entity Act.​

(3) The penalties for the following offences in Part VII of the Criminal Code Act are amended as follows:
Section 2 (Market Manipulation): Up to 500 Penalty Units; Up to 60 minutes imprisonment.
Section 4 (Third-Party Misrepresentation): Up to 400 Penalty Units; Up to 30 minutes imprisonment.
Section 6 (Embezzlement): Up to 1000 Penalty Units; Up to 60 minutes imprisonment; Restitution of the misappropriated assets or their value.
Section 7 (Fraud): Up to 1000 Penalty Units; Up to 60 minutes imprisonment; Restitution of the loss or its value.
Section 8 (Concealment of Criminal Proceeds): Up to 1000 Penalty Units; Up to 60 minutes imprisonment.
Section 10 (Exploitation of New Players): Up to 500 Penalty Units; Up to 30 minutes imprisonment.
Section 14 (Tax Evasion): Up to 500 Penalty Units; Up to 30 minutes imprisonment.
Section 15 (Market Allocation): Up to 500 Penalty Units; Up to 30 minutes imprisonment.
Section 16 (Bid Rigging): Up to 500 Penalty Units; Up to 30 minutes imprisonment.
Section 17 (Price Fixing): Up to 500 Penalty Units; Up to 30 minutes imprisonment.
Section 18 (Monopolisation): Up to 500 Penalty Units; Up to 30 minutes imprisonment; Forced divestiture of entities.
Section 21 (Unrecognized Foreign Exchange): Up to 500 Penalty Units; Up to 60 minutes imprisonment.
Section 22 (Foreign Exchange Fraud): Up to 500 Penalty Units; Up to 60 minutes imprisonment.
​

(4) Sections 26 to 30 of Part VII of the Criminal Code Act, being the offences inserted by Part V of the Banking Income Tax Act, are amended by substituting a reference to Part IX of the Commercial Standards Act for every reference to the Banking Income Tax Act, and Section 30 (Liability of Directors and Officers) is further amended as follows:
(a) A financial institution commits an offence under Sections 26 to 29; and​
(a) a financial institution, or an operation carrying on regulated financial activity, commits an offence under Sections 26 to 29 or under any offence inserted by the Commercial Standards Act; and​

(5) The offences inserted into Part VII of the Criminal Code Act by Section 34(1) of the Financial Institutions Enforcement Act are repealed, being:
Operating an Unregistered Financial Institution; Aggravated Operation of an Unregistered Financial Institution; Operating a Ponzi or Pyramid Scheme; Misuse of Client Funds; Breach of a Cease and Desist Order; Dissipation of Frozen Funds; Breach of a Product Intervention or Trading Suspension Order; Obstruction of Financial Regulation; Tipping Off; False Representation as a Financial Institution; Unlawful Offering of a Security or Financial Product; Reckless Facilitation of Unregistered Financial Activity; Operating or Participating While Barred or Disqualified; Liability of Operators, Directors, and Officers.​

(6) The offences added by subsection (1) replace those repealed by subsection (5). Conduct occurring before the enactment of this Act remains chargeable under the offence in force at the time it occurred, in accordance with Part I, Section 6(3) of the Criminal Code Act.

(7) Nothing in this section affects Section 3 (Insider Trading), Section 20 (Usury) or Section 31 (Violation of the Credit Standards Act) of Part VII, or Sections 32 to 39 of Part VII, being the offences inserted by the Bankruptcy Act.

57. Amendments to the Redmont Civil Code Act

(1) Part X of the Redmont Civil Code Act is amended by adding the following violations, each with the Commercial Standards Act as its Relevant Law:
Breach of the Commercial Standards Act
Violation Type: Administrative
Remedy: Up to 250 Civil Penalty Units; Compliance order; Disgorgement; Restitution; Receivership

A person commits a violation if the person:

(a) carries on or facilitates regulated financial activity in contravention of the Commercial Standards Act; or

(b) fails to comply with a lawful order or sanction of the Department of Commerce under that Act.
This violation shall not occur where:

(c) the person is taking reasonable steps to remedy their compliance.
​
Failure to Licence a Financial Institution
Violation Type: Administrative
Remedy: Up to 250 Civil Penalty Units; Compliance order

A person commits a violation if the person:

(a) carries on regulated financial activity without being licensed and incorporated as required by the Commercial Standards Act.
This violation shall not occur where:

(b) the person is taking reasonable steps to obtain a licence, or to cease the activity and return customer funds.
​
Breach of Client-Fund Segregation Duty
Violation Type: Strict Liability
Remedy: Restitution; Up to 250 Civil Penalty Units; Disgorgement

A person commits a violation if the person:

(a) receives or holds client funds; and

(b) fails to segregate them from the person's own funds, or applies them otherwise than as permitted under the Commercial Standards Act.
This violation shall not occur where:

(c) the funds were applied strictly as agent under the customer's mandate.
​
Failure to Honour Withdrawal or Redemption
Violation Type: Strict Liability
Remedy: Specific performance; Restitution; Up to 200 Civil Penalty Units

A person commits a violation if the person, without lawful excuse, fails to honour a customer's valid withdrawal, redemption or repayment request within the time required by the agreement or by law.
This violation shall not occur where:

(b) performance was prevented by a Freeze Order, court order or other lawful restraint.
​
Mis-selling of a Financial Product
Violation Type: Intentional/Negligent
Remedy: Rescission; Restitution; Up to 250 Civil Penalty Units

A person commits a violation if the person:

(a) recommends, sells or supplies a financial product to a customer;

(b) the product is unsuitable for that customer, or is supplied without fair disclosure of its risks, returns, fees or the possibility of loss of principal; and

(c) the customer suffers loss as a result.
This violation shall not occur where:

(d) the customer was a sophisticated party who did not rely on the person's recommendation.
​
Misleading Promotion of a Financial Product
Violation Type: Intentional/Negligent
Remedy: Up to 250 Civil Penalty Units; An order for corrective disclosure

A person commits a violation if the person:

(a) promotes a deposit or financial product using representations of fixed, guaranteed, insured or risk free returns; and

(b) those representations are false, or are not reasonably substantiated at the time they are made.
This violation shall not occur where:

(c) the representation constitutes puffery on which no reasonable person would rely.
​
Failure to File a Required Report or Return
Violation Type: Administrative
Remedy: Up to 100 Civil Penalty Units per failure; Compliance order

A person commits a violation if the person, being required to report under Part VIII or Part IX of the Commercial Standards Act, fails to file within the time required.
​
Failure to Comply with an Audit Demand
Violation Type: Administrative
Remedy: Up to 250 Civil Penalty Units; Adverse inference

A person commits a violation if the person fails to obtain and submit an independent audit required under the Commercial Standards Act, or obstructs such an audit or an independent monitor.
​

PART XII — REPEALS, AMENDMENTS AND TRANSITION

58. Amendments to Other Acts


(1) Section 5 (Alternative Financial Institution Taxes) of the Taxation Act is repealed, its subject matter being restated in section 34 of this Act.

(2) Section 6 (Powers of the Department of Commerce) of the Taxation Act is repealed, its subject matter being restated in Parts II and X of this Act.

(3) Section 7 (Deposit Guarantee) of the Taxation Act is repealed, its subject matter being restated in section 24 of this Act.

(4) Section 8 (Financial Institution Rights) of the Taxation Act is repealed, its subject matter being restated in section 9 of this Act.

(5) A reference in the Taxation Act or any other enactment to the taxation of financial institutions, or to the computation of their income, is read as a reference to Part IX of this Act.

(6) Section 25(1)(b) of the Bankruptcy Act is amended as follows:
Class 2: Customer deposits, up to the deposit guarantee limit under the Taxation Act, as that limit may be set from time to time;​
Class 2: Customer deposits and client funds, up to the deposit guarantee limit under the Commercial Standards Act, as that limit may be set from time to time. Client funds held in accordance with section 22 of that Act are the property of the customer and do not form part of the estate at all.​

(7) Section 32(1) of the Bankruptcy Act is amended as follows:
Where the debtor is a Financial Institution, the Department of Commerce retains primary authority under the Taxation Act and the Seizure and Insurance Adjustment Act.​
Where the debtor is a Financial Institution, the Department of Commerce retains primary authority under the Commercial Standards Act and the Seizure and Insurance Adjustment Act.​

(8) Section 32(3)(b) of the Bankruptcy Act is amended by substituting a reference to the Commercial Standards Act for the reference to the Taxation Act.

(9) Section 18(1) of the Bankruptcy Act is amended by deleting the words "including sole proprietorships", sole proprietorships being dealt with under Section 18(2) of that Act and not being Incorporated Entities under the Legal Entity Act.

(10) The Credit Standards Act continues in force and applies to every extension of credit by a Class H Credit Provider and by any other licensed institution. A failure to make the disclosures that Act requires is a contravention of this Act as well as an offence under Section 31 of Part VII of the Criminal Code Act.

59. Continuity of Licences and Registrations

(1) A person registered as a financial institution immediately before the enactment of this Act holds a licence for the corresponding class, being:

(a) Commercial Bank, Class A;

(b) Credit Union, Class B;

(c) Investment Bank, Class C; and

(d) Stock Exchange, Class F.

(2) A person who, immediately before the enactment of this Act, was lawfully carrying on an activity that this Act brings within a new licence class has 30 days to apply for that licence, and may continue the activity while the application is pending.

(3) A registration, exemption, order, undertaking, ruling, warning, Bar Order or sanction made under a repealed Act continues in force as if made under the corresponding provision of this Act.

(4) A rule made under a repealed Act continues in force so far as it is consistent with this Act.

(5) An institution licensed under subsection (1) has 90 days from the enactment of this Act to meet the capital requirement in section 16(5), and shall file a plan to do so within 30 days. This period is a maximum and the Department may not extend it.

(6) An institution that does not meet the requirement within the applicable period shall either surrender its licence and return customer funds in an orderly manner, or apply for a licence class whose requirement it does meet. The Department may act under Part X where it does neither.

(7) Section 18(5) does not apply to a qualifying holding acquired before the enactment of this Act, but the holder shall notify the Department of it within 30 days.

60. Transition

(1) This Act applies to regulated financial activity carried on before, on or after its enactment, and to all outstanding customer funds and deposits, regardless of when the activity commenced or the funds were received.

(2) The supervisory, recovery and remedial powers in Part X and the liability in section 53 apply to conduct, activity and funds arising before or after the enactment of this Act.

(3) A person carrying on regulated financial activity without a licence shall, within 7 days of the enactment of this Act, either apply for a licence or cease the activity and return all customer funds. A person who has applied within that period may continue the activity while the application is pending unless the Department directs otherwise.

(4) An offence under Part XI is committed only where the relevant conduct occurs on or after the enactment of this Act.

(5) A taxation period that commenced before the enactment of this Act continues to be governed by the law as it stood immediately before that time. A loss arising under the repealed Banking Income Tax Act or the Taxation Act is carried forward for no more than 3 months from the enactment of this Act.

(6) An amendment made to another Act by a repealed Act named in Section 1(5) survives the repeal except where this Act expressly provides otherwise, and a reference in any surviving amendment to a repealed Act is read as a reference to the corresponding provision of this Act.

(7) The first report due under Part VIII from a Tier 2 or Tier 3 reporting person is due at the end of its first full reporting period after the enactment of this Act.

(8) Nothing in this Act affects an existing legal action or a liability already accrued.

61. Relationship to Other Acts

(1) This Act supplements and does not limit the Redmont Corporate Entities Act, the Criminal Code Act or the Redmont Civil Code Act.

(2) Where this Act and another enactment both address the substance of a deposit or a financial product, they are read consistently and in favour of preventing avoidance.

(3) A reference in any enactment to the Commercial Standards Act, the Financial Institutions Enforcement Act or the Banking Income Tax Act is read as a reference to this Act.

62. Severability

(1) If any provision of this Act is held invalid or unenforceable, the remainder continues in full force and effect.[/B]
 
Last edited by a moderator:
Nay - "Super Acts" like this one are, with few exceptions, too complicated for the average citizen to read and understand.

Having these regulations spread out across the four acts they're already in actually helps readability.

Furthermore, making this "Super Act" makes it far too easy to hide clauses in here and makes it difficult for us to determine what has actually changed.
Since people are not satisfied with this, I'll state more reasons I am unhappy with this bill:

- DoC would get power to arbitrarily freeze assets (no due process for unreasonable seizure)
- DoC would get to access accounts of financial institutions (no due process for unreasonable search)
- DoC would get to make new licenses, requirements for licenses, and basically be a legislative body across all of finance
- Congress' Resolutions somehow have a force of law behind them in this Act despite being definition, not a force of law.
- Establishes gender (a non-existent concept in Minecraft), race (a non-existent concept in Minecraft), and political affiliation as protected statuses for employment.
- Establishes weird capital requirements for some things. Makes it extremely difficult to start a bank.
- Financial Institution costs are too high under this, with 25% in taxes, plus 6%+ in fees.
- 1% daily interest on unpaid tax is crippling
- DoC would get broad investigative power even to unlicensed and unincorporated people
- Only 7 days to appeal is ridiculous
- Wild ex-post-facto enforcement
 
Votes before S-49/39
 

Attachments

  • IMG_3158.jpeg
    IMG_3158.jpeg
    281.9 KB · Views: 53
Aye, I believe in workers protections, but that can be dealt with in a separate bill instead of naying the whole bill because of the workers rights section.
 

Presidential Assent


Seal_President_Small.png


PRESIDENTIAL ASSENT​


This Act restates the law of commerce and finance in a single instrument. It repeals and replaces the Commercial Standards Act, the Financial Institutions Enforcement Act and the Banking Income Tax Act, opens a closed list of institutions into eight licence classes with a capital figure attached to each, replaces every separate reporting obligation with one tiered return, restates the taxation of financial institutions in one Part, and states the Department's enforcement powers as a single ordered escalation with notice and appeal at each step.

I grant assent for two reasons.

First, the law it replaces could not be followed by the people it bound. Four Acts amended one another in both directions, a one player company owed the same monthly statements as the largest bank in Redmont, and the enforcement ladder written to protect depositors sat in an Act those subject to it had no reason to read. The paperwork this Act removes is larger than the paperwork it adds.

Second, the licence class ladder ends a closed market. Payments, custody, insurance and managed funds had no licence to apply for, so they operated unregulated or did not operate. Each now has a class, a capital figure and a supervisor, and Section 17 lets the Department bring the next one in without a further Act of Congress.

This Act is my own work, with Secretary Planke Fontaine. I record that here rather than leave it to be pointed out.

I record the following for Congress and for the Office of Congressional Affairs. These are not conditions of my assent.

1. The Act is cited as the Redmont Commerce and Finance Act at Section 1(1), but Parts XI and XII refer throughout to the Commercial Standards Act, including in the offences inserted into the Criminal Code Act. Section 61(3) reads those as references to this Act, so nothing fails, but the Criminal Code will carry offences citing a repealed statute by name until it is tidied.

2. There are no Sections 11 or 12. Part III ends at Section 10 and Part IV opens at Section 13.

3. Section 61(1) refers to the Redmont Corporate Entities Act, which is not yet law. Until it is, that reference is to be read as a reference to the Legal Entity Act.

4. The violation at Section 57(1) headed Failure to Honour Withdrawal or Redemption begins its lettering at (b).

My thanks to Commerce Secretary Planke Fontaine for co-authoring, and to Senator ElegantAlly for co-sponsoring.


This bill has been granted assent and is hereby signed into law.
signature

Theory Fontaine
30th President of the Commonwealth of Redmont​

 
CONGRESS OF THE
COMMONWEALTH OF REDMONT
​


A BILL TO
GIVE CREDIT WHERE IT'S DUE FOR REPEAL-AND-REPLACE LAWS AND SET PRECEDENT FOR FURTHER CREDITING


​


The people of the Commonwealth of Redmont, through their elected Representatives in the Congress and the force of law ordained to that Congress by the people through the constitution, do hereby enact the following provisions into law:
PART I: PRELIMINARIES
1. Short Title and Enactment
(1) This Act may be cited as the "RnR Common Courtesy Act" or the "RnRCCA".
(2) This Act shall be enacted immediately upon its signage.
(3) This Act has been authored by Speaker HatManMC, coauthored by Lxi404, and with review and guidance from Clerk and Representative EmeraldGuuy.
(4) This Act has been cosponsored by Representative EmeraldGuuy.
(5) This Act amends the following acts:
(a) Legislative Standards Act
(b) Bill & Resolution Formats
(c) Redmont Economic Standards Act
(d) Taxation Act
(e) Redmont Corporate Entities Act
(f) Redmont Commerce and Finance Act

(g) Redmont Family Law Act

2. Reasons and Intent
(1) Recently, a trend has appeared in bill writing, termed in this act as a "repeal-and-replace" or RnR act. In these acts, the original acts and amendments from which the new RnR bills draw significant material are entirely removed from the crediting process and the contributions of former authors to legislative works are lost.
(2) This act is not to discourage or stop the practice of Repeal and Replace Acts, but it does serve to credit the authors that contributed massively to the laws of this nation yet are not credited in current legislation.


PART II: DEFINITIONS
3. Definitions
(1) For the purposes of this Act and all other acts:

(a) Repeal and Replace Act/RnR Act. An Act that repeals an Act passed by the Congress of the Commonwealth of Redmont and attempts to serve completely in its stead - that is, fulfilled an equally encompassing or nearly equally encompassing jurisdiction in legislation.


PART III: AMENDMENTS
4. Legislative Standards Act & the Bill and Resolution Formats
(1) The following shall be inserted after §5(d)(iii) of the Legislative Standards Act:

(iii) If the sponsor refuses or fails to amend the title within 48 hours, the bill shall be rejected and moved to the Rejected sub-forum.

(6) Authorship Citations and Repeal and Replace (RnR) Acts
(1) Any bill posted must cite the author of the bill, being either the sole contributor to the writing or the largest contributor.

(2) If multiple contributors wrote the bill together, they are recommended to be put down as coauthors as to give them credit for their work.

(3) If a Bill repeals an Act previously passed by the Congress of the Commonwealth of Redmont and attempts to serve in its stead, while drawing a significant amount of material from the Act it repeals, one is obligated to write the author of the repealed bill and any authors of amendments to the source material as source authors (as shown in §1(3)(a) of the Bill & Resolution Formats).


(2) §1(3) of the Bill & Resolution Formats via §21 of the Legislative Standards Act shall be amended as follows:

(3) This Act has been authored by [Author Name].
(a) [if applicable] This Act is a repeal and replace of the [insert repealed bill], authored by [former author name], which included amendments authored by [former amendment authors names].

5. Redmont Economic Standards Act
(1) The following shall be inserted after §1(3) of the Redmont Economic Standards Act.

(3) This Act has been authored by President xXTheoryXx, Commerce Secretary Planke32.
(a) This Act is a repeal and replace of the Economic Standards Act, authored by Nacholebraa, which included amendments authored by lcn, CaseyLeFaye, UnityMaster, Avaneesh2008, JuliaMC_, winterwolf, girlfailcoded, Multiman155, Angryhamdog, xEndeavour, Stanley582, Dearev, EATB, and antonfr.

6. Taxation Act
(1) The following shall be inserted after §1(3) of the Taxation Act.

(3) This Act has been authored by President xXTheoryXx, Commerce Secretary Planke32.
(a) This Act is a repeal and replace of the Taxation Act, authored by xEndeavour, which included amendments authored by hugebob23456, 218218Consumer, xlayzur, Thritystone, Reaperay, RandomIntruder, Milkcrack, Dartanman, lcn, UnityMaster, xSyncx, Vernicia, Chaos_Canadian, Kaiserin_, gwiis, Anthony_Org, Omegabiebel, ToadKing, Vennefly, jJoshuaTheGreat, Incarnation__, TrueDarklander, Technofied, NullaPoene, and Gluonmaster.

7. Redmont Corporate Entities Act
(1) The following shall be inserted after §1(3) of the Redmont Corporate Entities Act.

(3) This Act has been authored by President Theory Fontaine, Commerce Secretary Planke Fontaine, and FRB Governeor Coshjlose.
(a) This Act is a repeal and replace of the Legal Entity Act, authored by zLost and Multiman155, which included amendments authored by ToadKing, Omegabiebel, Nullapoene, and MJL_.

8. Redmont Commerce and Finance Act
(1) The following shall be inserted after §1(3) of the Redmont Commerce and Finance Act.

(3) This Act has been authored by President Theory Fontaine, Commerce Secretary Planke Fontaine, and FRB Governeor Coshjlose.
(a) This Act is a repeal and replace of the Commercial Standards Act, Financial Institutions Enforcement Act, and the Banking Income Tax Act.
(i) The Commercial Standards Act was compiled by xEndeavour, and included amendments authored by Towloo, xSyncx, Anaphase_Andy, Avaneesh2008, YeetGlazer, Kaiserin_, Smallfries4, TrueDarklander, Nimq_, Pepecuu, .MgChamp2339, Jesseya (Kat), Omegabiebel, Anthony_Org, and Scassany.
(ii) The Financial Institutions Enforcement Act was authored by xXTheoryXx.
(iii) The Banking Income Tax Act was authored by jJoshuaTheGreat and Incarnation__.


9. Redmont Family Law Act
(1) The following shall be inserted after §1(3) of the Redmont Family Law Act:

(3) This Act has been authored by President Theory Fontaine.
(a) This Act is a repeal and replace of the Marriage Act and Adoption Act.
(i) The Marriage Act was proposed by Westray, and included amendments by xEndeavour, tair0, A__C, lawanoesepr, CaseyLeFaye, UnityMaster, and Multiman155.
(ii) The Adoption Act was proposed by Aladeen22, and included amendments by Rurge and Aladeen22.


PART IV: IMPLEMENTATION
10. Implementation
(1) The Office of Congressional Affairs is authorized to make any changes involving renumbering of sections as a result of edits made in this Act.
 
​

Presidential Assent


Seal_President_Small.png

​


The RnR Common Courtesy Act makes sure that the people who wrote and shaped our laws keep their credit when those laws are repealed and replaced. Over the past while, several major acts have been rewritten from scratch, and while the new versions drew heavily on the old ones, the original authors and everyone who amended them were left out of the credits entirely.

Going forward, the bill amends the Legislative Standards Act and the Bill & Resolution Formats so that every bill must name its author, coauthors are encouraged to be listed, and any repeal-and-replace bill that draws significantly on the act it repeals must credit that act's author and the authors of its amendments. It also corrects the record for the five recent repeal-and-replace laws by adding source credits to the Redmont Economic Standards Act, the Taxation Act, the Redmont Corporate Entities Act, the Redmont Commerce and Finance Act and the Redmont Family Law Act.

However: the new crediting requirement has no stated consequence if a bill leaves the source authors out, and "a significant amount of material" is not defined, so it will largely be up to the Clerk and the presiding officers to judge when a bill qualifies. In practice this should work as a strong expectation rather than a hard rule, and Congress may want to tighten it later if it is ignored.

Overall, this is a thoughtful and overdue measure that recognises the many legislators whose work still forms the backbone of our laws today.

I thank Speaker HatManMC for authoring this bill, Senator Lxi404 for coauthoring it, Representative EmeraldGuuy for reviewing and cosponsoring it, and Congress for passing it.

This bill has been granted assent and is hereby signed into law.

aMOcVMr.png

antonfr
President of the Commonwealth of Redmont​

 
Back
Top